


9 Nov, 26
Weekly Crypto Market Wrap: 9 November 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected] or visit our website www.zerocap.com
This is not financial advice. As always, do your own research.
Week in Review
- The RBA raised the cash rate 25bp to 4.85%, its fifth increase this year and the highest level since 2008, on a six-to-three vote with three members preferring to hold; the statement dropped its explicit reference to further tightening and AUD/USD fell to a two-week low near 0.6975.
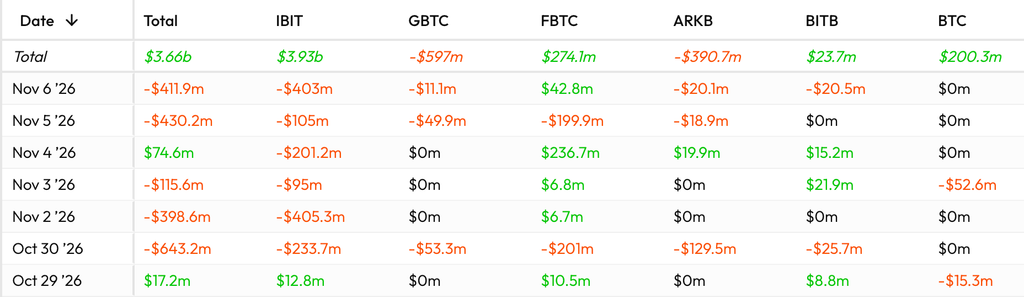
- U.S. spot Bitcoin ETF products shed US$1.28B over the week, their heaviest redemptions since June, pushing 2026 flows negative for the first time; Ethereum funds lost a further US$365.3M in a sixth consecutive week of outflows.
- Democrats took control of both chambers at the midterms, and House Democrats began discussing legislation that would expand SEC oversight of digital assets and narrow the CFTC’s role, drawing on Representative Maxine Waters’ earlier investor protection package.
- More than US$1B of leveraged positions were liquidated as BTC fell to an intraday low of US$74,780 on Friday, its weakest since 21 August, with longs accounting for roughly 88% of the total.
- FinCEN and the Federal Reserve Board withdrew their proposed US$250 threshold for recordkeeping and travel-rule requirements on cross-border transfers, effective 9 November.
Technicals & Macro
Markets
The midterms were supposed to remove uncertainty. For one day they did. Democrats took both chambers of Congress, with a 54-44 Senate and a net gain of seven seats, and President Trump accepted the result. Markets welcomed the clarity: the Dow rose more than 1,500 points on Wednesday, its best day since April 2025, helped by a sharp fall in oil.
Then the market started pricing what a Democratic Congress means for AI. On Thursday the S&P 500 fell 4.4% and the Nasdaq 100 lost 6.4%, wiping out a record US$2.3 trillion in a single session. The concern is specific: tighter oversight of AI and more resistance to the data centre buildout, which would hit chip and power demand directly. The semiconductor index fell 12%, AMD 17% and Nvidia 9%, and utilities tied to AI power demand fell with them. The VIX jumped around 70%.
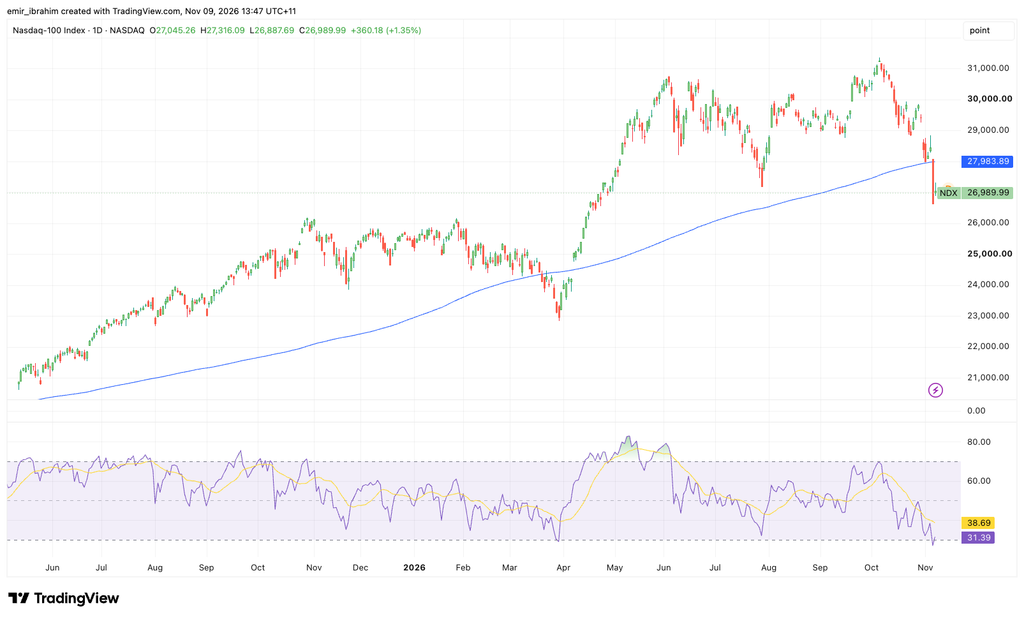
Friday brought a partial bounce, but the S&P 500 still finished the week down 2.7% at 7,376.86, its worst week since the April 2025 tariff shock. The Nasdaq fell 3.4% to 24,579.42, is now in correction, and has fallen for four straight weeks. A month ago the debate was whether AI spending would pay off. It now includes whether it will be allowed to continue at the same pace.
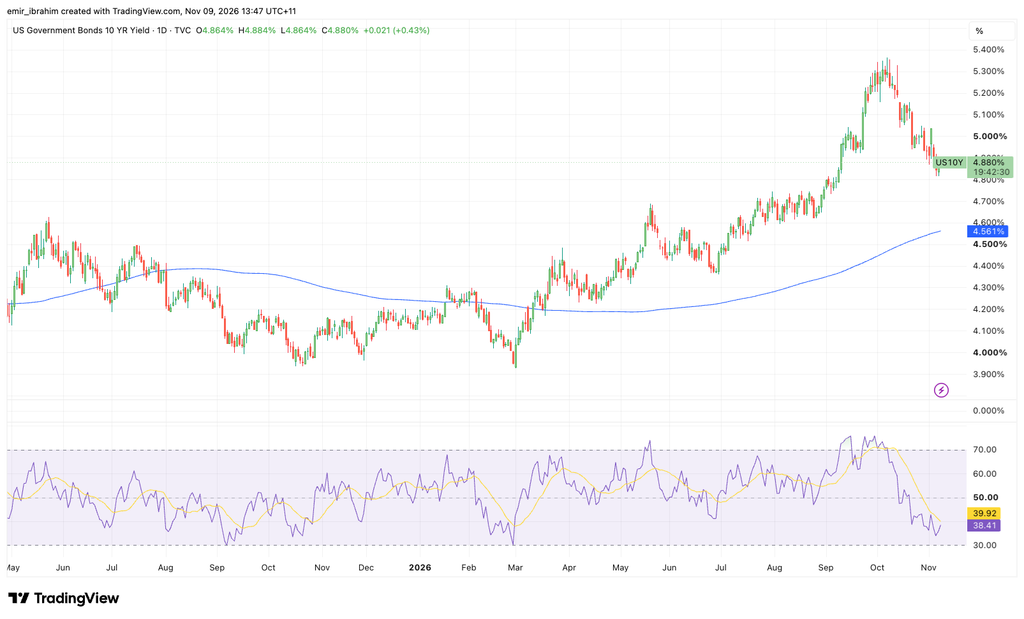
Friday’s payrolls made the backdrop harder. The US added 165,000 jobs in October against expectations of 59,000, unemployment fell to 4.1% and wages rose 0.4% on the month, with earlier months revised up. That pushed yields higher, with the 10-year back near 4.86%, and firmed pricing for a December Fed hike. Tuesday’s October CPI is now the deciding input.
Oil was the one source of relief. Brent fell around US$15 over the week to roughly US$96, as the election shifted expectations around the Iran war. The Bank of England cited exactly that when it raised rates for the first time in three years, to 4.00%, noting that a sustained fall in energy prices could limit the need for further hikes. The vote was 8-1, with one member pushing for 50 basis points.
Source: Velo.xyz
For crypto, institutional retreat is the bigger concern. Spot Bitcoin ETFs lost US$1.28 billion over the week, the most since June, with BlackRock’s IBIT accounting for almost all of it. That pushed 2026 ETF flows back below zero. Ether ETFs posted a sixth straight weekly outflow. A Democratic Congress is also seen as less supportive of digital asset regulation, which adds to the case for caution among allocators.
Source: SaylorTracker.com
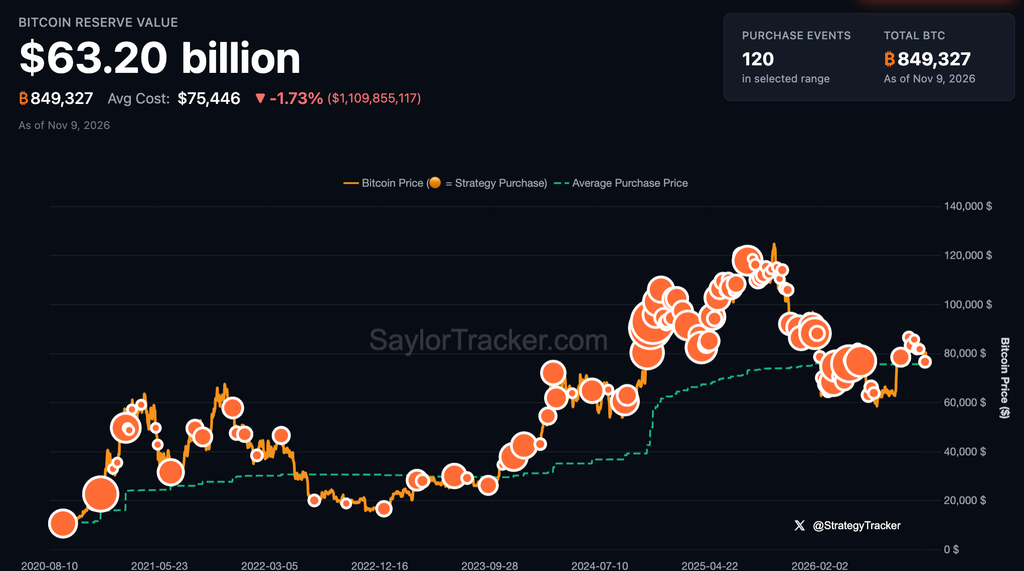
The name to watch this week is Strategy. Bitcoin is now below its average cost of around US$75,450 across roughly 849,000 BTC. Strategy has said none of its Bitcoin is pledged as collateral and it holds around US$4.8 billion in reserves for dividends and interest, so forced selling is not the issue. But MSCI publishes its list of companies affected by its new index rules on Wednesday, and an exclusion landing while Bitcoin sits below Strategy’s cost basis would test confidence in the largest corporate holder.
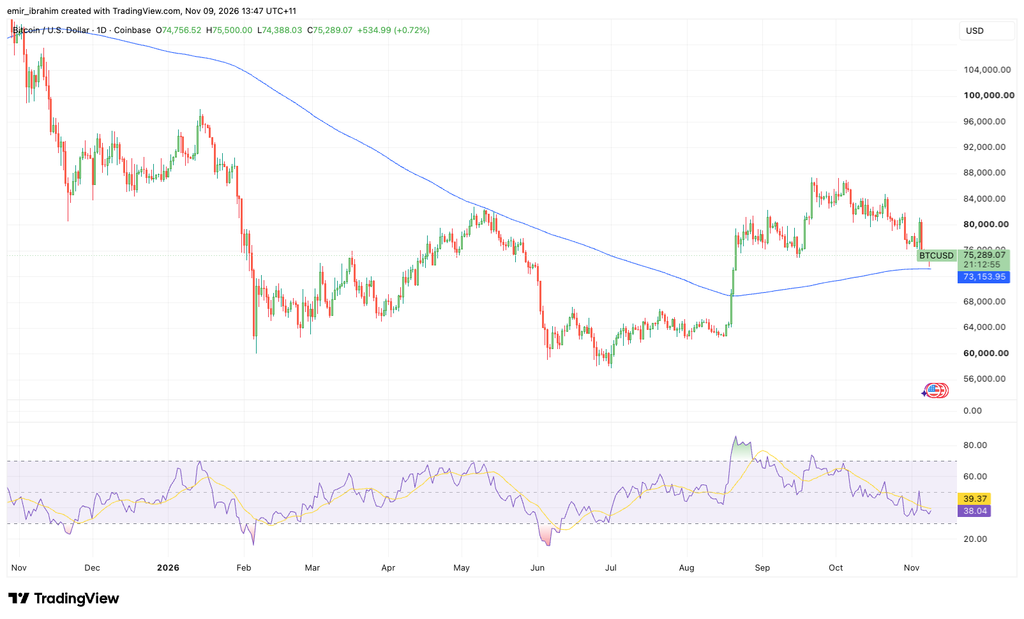
We expect the 200-day average near US$73,000 to hold through CPI, given how much selling has already gone through ETFs and futures. A daily close below it opens a move toward US$70,000. A move back above US$77,000 needs ETF outflows to stop and a CPI print that doesn’t harden December.
Emir Ibrahim
Spot Desk
Digital assets weakened through the week, with BTC briefly recovering above US$80,000 on the midterm result before giving it back and trading to its lowest level since August by Friday. ETH underperformed on the cross, falling more than 7% in a single session midweek. The pressure was external rather than crypto-specific, with a renewed tech and AI selloff and a firmer October payrolls print lifting December hike pricing and weighing on liquidity-sensitive assets.
On the desk, stablecoin offramping drove the book and ran at roughly double the prior week’s pace, the heaviest we have seen this year. USDT carried an overwhelming net selling skew with USD the counterpart, while USDC was also offered. AUDD remained significantly net sold.
Activity in digital assets stayed thin but turned more one-directional than in recent weeks. ETH was net bought while BTC saw a marginal selling skew, and the long tail was liquidated almost uniformly, with SOL, ADA, DYDX, CRV, ZRX and COMP all offered without buy interest against them.
In FX, the RBA raised the cash rate 25bp to 4.85% on Tuesday, its fifth increase this year and the highest level since 2008, following September CPI at 4.3%. The vote was six to three, however, and the statement dropped its explicit reference to further tightening, which the market read as the end of the cycle rather than a continuation of it; AUD/USD fell to a two-week low near 0.6975 in the hours afterwards and pricing for a move to 5.10% halved. The Bank nonetheless lifted its December 2026 CPI forecast sharply in Friday’s Statement on Monetary Policy. With the next decision not until 8 December, the near-term AUD impulse now rests more on USD direction than domestic pricing. On the desk, USD was significantly net bought, GBP and NZD both bought on a one-way basis, AUD modestly bought, and EUR offered.
The OTC desk continues to provide tailored cryptocurrency liquidity solutions and competitive pricing across major digital assets, stablecoins, selected altcoins and key fiat currency pairs. With T+0 settlement capability, the desk continues to facilitate efficient execution and settlement across client flows.
Oliver Davis, OTC Trader
Derivatives Desk
WHOLESALE INVESTORS ONLY
Spot demand has remained soft for BTC: U.S. spot Bitcoin ETFs recorded approximately $1.28bn of net outflows over the five sessions to 6 November, their largest weekly outflow since late June.
The derivatives market has now experienced two significant leverage flushes in the space of a few days. Thursday’s equity-led sell-off triggered approximately $1.26bn of crypto liquidations, including $1.12bn of longs. Then on Sunday, another sharp BTC move toward $73.8k generated more than $1bn of liquidations, with roughly $913m of bullish positions wiped out. BTC itself accounted for around $272m of Sunday’s liquidations.
Aggregate BTC futures open interest currently sits around $51.3bn, according to CoinGlass, down only 1.7% over the latest 24-hour window. Leverage has been forcibly reduced during the sell-off, rather than continuing to expand against falling spot. This is healthier structurally, even if it has done little to arrest the immediate price weakness.
Perpetual funding has held up considerably well given the volatility across all markets this week, illustrating that there are some notable hedging and/or speculative flows even in the face of increasing uncertainty.
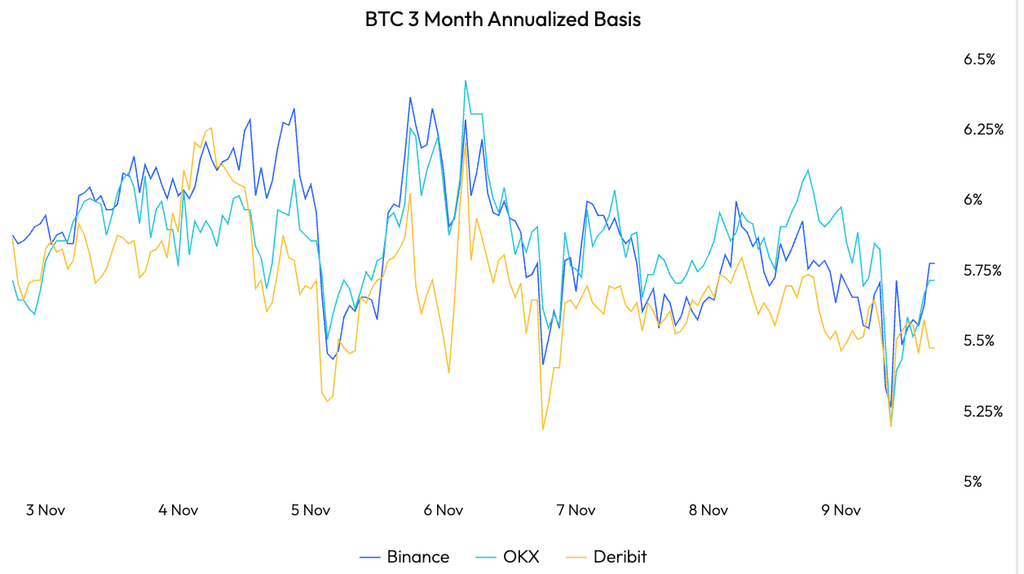
The dated curve has also remained remarkably resilient throughout the sell-off. BTC’s 90-day annualised basis is still holding above 5.5% p.a, which is continuing to normalise against a year of compression. A basis curve above 7% becomes very interesting given the hunt for yield above benchmark rates from investors.
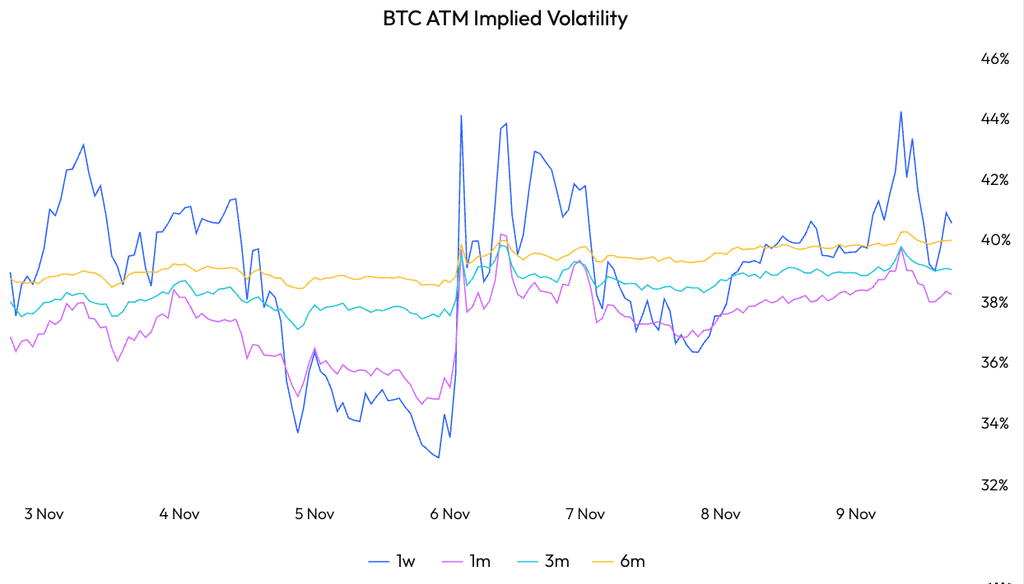
The midterm election premium initially disappeared very quickly: following the result, one-week BTC implied volatility fell from around 41% to approximately 34% as the discrete event risk cleared. That relief proved short-lived. Renewed weakness in equities and BTC has subsequently driven 1-week ATM IV back to 40.36%, versus 38.80% at two weeks and 38.47% at one month. The front end of the curve is therefore inverted again, with traders paying more for immediate volatility than for protection further out.
Downside skew has also rebuilt. BTC 25-delta risk reversals currently sit at -4.44 vols for 1-week, -4.31 for 2-week and -3.63 for 1-month. Puts are trading materially richer than equivalent calls, with the premium concentrated toward the front of the curve. Importantly, however, outright volatility is not dramatically expensive relative to what BTC is actually doing: 7-day realised volatility is approximately 38.37% versus 1-week implied at 40.36%. Investors are paying roughly two volatility points over trailing realised for near-term protection — elevated, but hardly panic pricing.
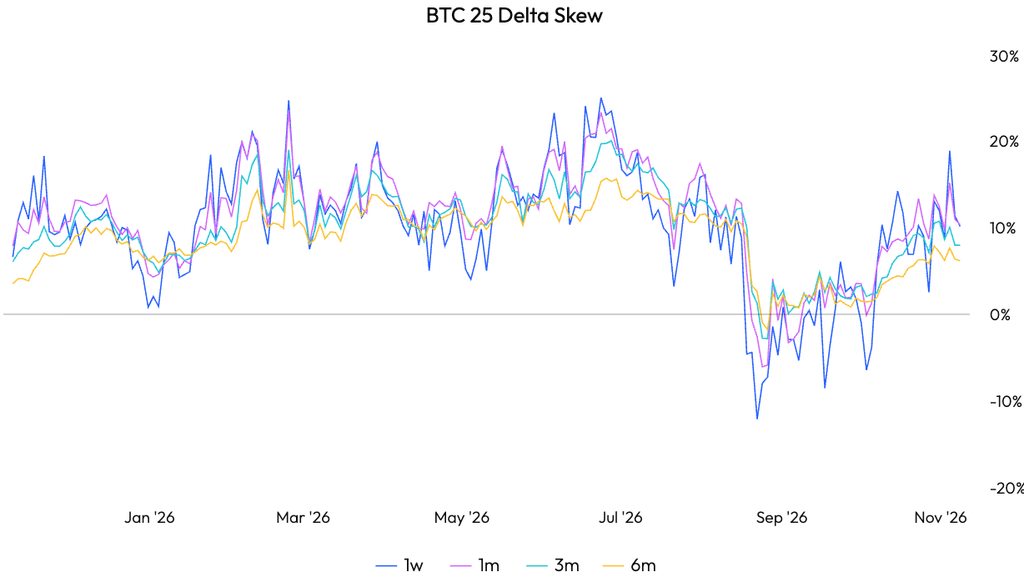
This distinction matters. The market briefly priced the midterms as a discrete volatility event, removed that premium once the result was known, and has now rebuilt short-dated protection because underlying risk conditions have deteriorated. The combination of repeated long liquidations, ETF outflows and persistent put skew suggests investors remain cautious, even though the futures curve itself continues to normalise.
Overall, the derivatives market looks deleveraged but defensive rather than structurally stressed. Leverage has been flushed twice, funding has normalised and dated basis remains around the mid-5% range. The principal risk signal is coming from the options surface, where short-dated volatility is inverted and investors continue to pay a premium for downside.
Safe trading out there!
Jon de Wet, CIO
What to Watch
Tue: US Inflation Rate, US Core Inflation Rate, Fed Waller Speech
Wed: DE Inflation Rate, US EIA Crude Oil Stocks
Thu: US Initial Jobless Claims, GB GDP, NZ Inflation Expectations
Fri: US PPI, US Core PPI, EA GDP Growth Rate Q3
Disclaimer
This material is issued by Zerocap Pty Ltd (Zerocap), a Corporate Authorised Representative (CAR: 001289130) of Gannet Capital Pty Ltd (GC) AFSL 340799.
Material covering regulated financial products is issued to you on the basis that you qualify as a “Wholesale Investor” for the purposes of Sections 761GA and 708(10) of the Corporations Act 2001 (Cth) (Sophisticated/Wholesale Client), or your local equivalent.
This material is intended solely for the information of the particular person to whom it was provided by Zerocap and should not be relied upon by any other person. The information contained in this material is general in nature and does not constitute advice, take into account financial objectives or situation of an investor; nor a recommendation to deal. Any recipients of this material acknowledge and agree that they must conduct and have conducted their own due diligence investigation and have not relied upon any representations of Zerocap, its officers, employees, representatives or associates. Zerocap has not independently verified the information contained in this material. Zerocap assumes no responsibility for updating any information, views or opinions contained in this material or for correcting any error or omission which may become apparent after the material has been issued. Zerocap does not give any warranty as to the accuracy, reliability or completeness of advice or information which is contained in this material. Except insofar as liability under any statute cannot be excluded, Zerocap and its officers, employees, representatives or associates do not accept any liability (whether arising in contract, in tort or negligence or otherwise) for any error or omission in this material or for any resulting loss or damage (whether direct, indirect, consequential or otherwise) suffered by the recipient of this material or any other person. This is a private communication and was not intended for public circulation or publication or for the use of any third party. This material must not be distributed or released in the United States. It may only be provided to persons who are outside the United States and are not acting for the account or benefit of, “US Persons” in connection with transactions that would be “offshore transactions” (as such terms are defined in Regulation S under the U.S. Securities Act of 1933, as amended (the “Securities Act”)). This material does not, and is not intended to, constitute an offer or invitation in the United States, or in any other place or jurisdiction in which, or to any person to whom, it would not be lawful to make such an offer or invitation. If you are not the intended recipient of this material, please notify Zerocap immediately and destroy all copies of this material, whether held in electronic or printed form or otherwise.
Disclosure of Interest: Zerocap, its officers, employees, representatives and associates within the meaning of Chapter 7 of the Corporations Act may receive commissions and management fees from transactions involving securities referred to in this material (which its representatives may directly share) and may from time to time hold interests in the assets referred to in this material. Investors should consider this material as only a single factor in making their investment decision.
Contact Us
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
Like this article? Share
 Share
 Tweet
 Post

Latest Insights
Weekly Crypto Market Wrap: 4 November 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 26 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 20 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Receive Our Insights
Subscribe to receive our publications in newsletter format — the best way to stay informed about crypto asset market trends and topics.