


20 Oct, 26
Weekly Crypto Market Wrap: 20 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
This is not financial advice. As always, do your own research.
Week in Review
- Bitmine added 12,535 ETH to reach 6.04M ETH (4.9% of supply) in continued crypto treasury accumulation; Strategy purchased a further 267 BTC for US$22.1M.
- U.S. spot Bitcoin ETF products recorded US$228M in net outflows; Ethereum ETFs shed US$320M.
- MSCI introduced new index eligibility rules for non-operating companies; digital asset treasury firms Strategy, Metaplanet and SharpLink at risk of exclusion.
- USDC becomes the first stablecoin classified as a “significant” e-money token under EU MiCA rules; reserves and liquidity now brought under direct EBA oversight.
- BlackRock filed for a new Bitcoin ETF offering capped upside exposure alongside downside protection; expanding its suite of record-breaking institutional BTC investment products.
Technicals & Macro
Markets
Inflation and the AI trade defined last week. September CPI, released Wednesday, rose 0.6 percent on the month and 3.7 percent on the year, up from 3.4 percent and above the 3.6 percent consensus. More concerning was the core measure, which accelerated to 2.6 percent from a five-year low of 2.4 percent, against expectations of 2.5 percent, signalling that price pressures are broadening beyond energy. Producer prices also surprised to the upside. Oil compounded the picture: Brent touched US$110 on Friday for the first time since May, settling at US$109.86 for a weekly gain of 4.9 percent, as at least nine commercial vessels came under attack near Hormuz and Houthi forces again targeted Saudi Arabia. WTI rose more than 10 percent to US$101.41.
The bond market’s reaction was, perhaps counterintuitively, a rally. The 10-year yield fell around 14 basis points over the week to roughly 5.09 percent, and the 2-year eased to around 4.72 percent. Two factors explain it. First, the sell-off in equities prompted a flight to safety. Second, Chair Warsh, speaking at the IMF meetings in Bangkok, declined to signal another hike, stating that he does not prejudge meetings and that the hotter inflation data had not altered his assessment of the economy. Goldman Sachs read the comments as confirming an October pause. Markets now price roughly an 85 percent chance of a hold on 27-28 October, while a December increase remains around 77 percent priced. In our view the Fed has effectively shifted the decision to December, and October’s statement language will matter more than the outcome.
Equities had their worst week since June. The Nasdaq fell 4.5 percent to 26,140.03 and the S&P 500 lost 2.0 percent to 7,659.44, as the semiconductor index extended its losing run to eight sessions, matching its longest since 2006. The driver was a growing concern that higher rates will constrain AI infrastructure spending, with data centre operators and neoclouds hit hardest. The Dow bucked the trend, gaining 0.7 percent as capital rotated toward old-economy names. Monday brought partial relief, with the Nasdaq up 1.1 percent and the semiconductor index snapping its streak, though breadth outside technology remained weak. This week’s earnings from SpaceX, Meta, Tesla and IBM will be the first real test of whether AI capex guidance can steady the trade.
Domestically, September employment fell 39,300 against expectations of a 20,000 gain, and the unemployment rate held at 4.7 percent, its highest since 2021, after August was revised up. The data strengthens the case that the RBA’s four hikes this year are now transmitting into the labour market, and November hike pricing fell to around 15 percent. That said, Westpac continues to expect a November increase, and the September quarter CPI on 28 October will be decisive..
Cryptocurrency
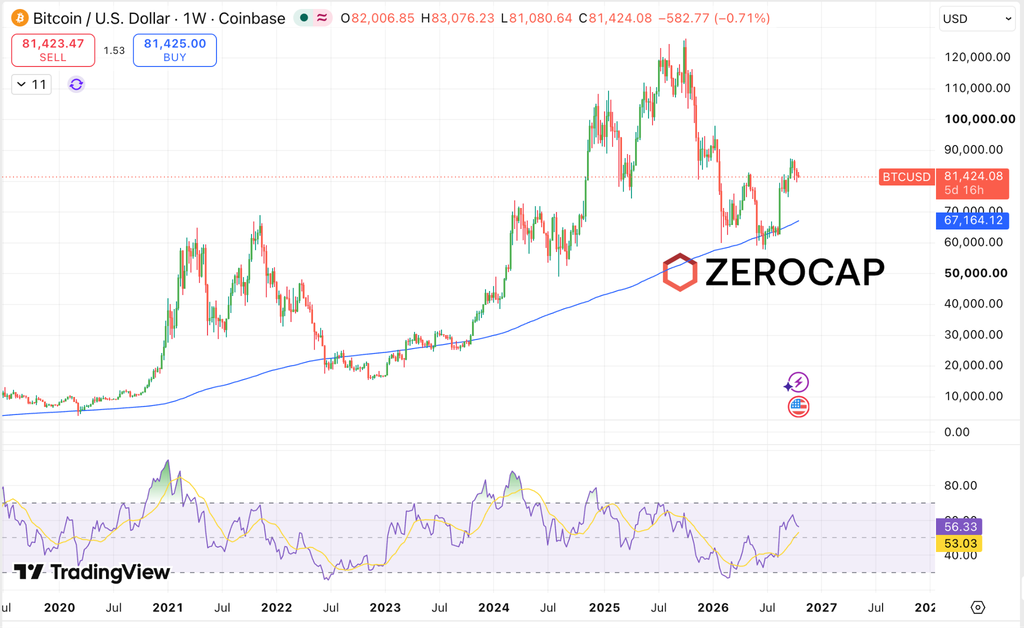
Crypto traded with risk assets, selling off with technology on Wednesday’s CPI print before stabilising into the weekend. Bitcoin briefly dipped below US$80,000 on Friday, trading in a range of US$79,676 to US$84,262 over the week, and sits near US$81,992 this morning, down approximately 2.2 percent. Ether fell around 5.6 percent to US$2,409 and Solana around 6.1 percent to US$105.10. Around US$970 million of positions were liquidated on the day of the inflation release, predominantly longs. Breadth was poor, with 86 of the top 100 tokens lower and Bitcoin dominance rising, which points to consolidation into Bitcoin rather than rotation out of it.
Institutional demand weakened for a second consecutive week. US crypto ETFs recorded approximately US$611 million of net outflows, following US$1.29 billion the week prior. Ether products accounted for the larger share at US$320 million, almost all from BlackRock’s ETHA, while Bitcoin funds shed US$228 million.
Selective strength persisted beneath the surface. Bitway extended its run by close to 50 percent, its seventh consecutive week of new highs, and AI-focused Pearl reached a record above US$2. Monero gained around 10 percent to roughly US$590, a notable divergence from Zcash, which suggests the market is distinguishing between privacy designs rather than trading the sector as one. On the other side, Starknet gave back almost half its value after governance voted to transition the network to a layer one, reversing the prior week’s 88 percent gain, while Pump.fun and Raydium each fell more than 25 percent.
The more significant developments were structural and continue the institutionalisation thread we have tracked through the year. Europe’s banking regulator took direct oversight of the second-largest stablecoin, BNY financed a tokenised Treasury within a live repo workflow, and Interactive Brokers began offering Ether staking to clients. None moved price last week, but together they reinforce that the infrastructure buildout is continuing regardless of the tape.
For positioning, Bitcoin has now defended the US$80,000 level twice in a fortnight, which approximates the average ETF cost basis. That is constructive, but with two weeks of outflows and the next macro catalyst, a Fed meeting where December is the live question, we would expect range trading between US$80,000 and US$87,000 until institutional flows turn.
For any pricing needs, please get in touch.
Emir Ibrahim
Spot Desk
Digital assets traded defensively for a second consecutive week as AI-led risk aversion weighed on institutional appetite and ETF outflows persisted, while MSCI’s potential exclusion of Strategy, Metaplanet and SharpLink added further technical overhang for treasury names. Despite the broader equity rout, crypto held up relatively well, with majors briefly sweeping the prior week’s lows before recovering them on a closing basis. Strategic accumulation also persisted: Strategy (MSTR) added 267 BTC, while Bitmine (BMNR) lifted its ETH treasury to 6.04M ETH, roughly 4.9% of circulating supply as they near their stated 5% target.
Desk flows broadly tracked the institutional tape; BTC carried a net selling skew in line with ETF redemptions and weaker aggregate risk appetite, while ETH was modestly net bought, a countertrend outcome against both its relative underperformance and another sizable week of passive outflows. Participation further out the risk curve was limited as breadth compressed, though long-time client favourite Hyperliquid (HYPE) continued to attract selective buying.
In FX, a broadly unchanged weekly close masked a more volatile path for AUD/USD. Opening at 0.6969, the pair traded down to 0.6894 after Thursday’s labour force release showed the domestic unemployment rate holding at 4.7%, above expectations. The immediate read was dovish: evidence that tighter financial conditions are cooling labour demand weighed on AUD as the market-implied probability of a November hike by the RBA fell from 27% to 16%; however, the move proved short-lived. AUD pared much of the decline by Friday’s New York close and has continued to firm into the new week, currently trading at 0.6983 as hike odds rebuild to 22%. The RBA’s September meeting minutes were firmly hawkish on materialising inflation risks; however, with unemployment now above the Bank’s 4.6% NAIRU, Governor Bullock’s “a little tight” framing becomes harder to defend. With domestic policy caught between a cooling labour market and persistent inflation risk, relative-rate repricing and broader USD direction remain the key near-term drivers for AUD. On the desk, AUD was net bought, EUR offered and NZD bought.
In stablecoins, USDT recorded one of its largest off-ramping weeks of the year as the risk-off tone brought out a pronounced preference for USD liquidity, while USDC continued to diverge with a net on-ramping skew. AUDD was significantly offered as clients continued to use alternative local rails to move into USD-denominated stablecoins.
The OTC desk continues to provide tailored cryptocurrency liquidity solutions and competitive pricing across major digital assets, stablecoins, selected altcoins and key fiat currency pairs. With T+0 settlement capability, the desk continues to facilitate efficient execution and settlement across client flows.
Ben Mensah, OTC Trader
Derivatives Desk
WHOLESALE INVESTORS ONLY
BTC remains range-bound at ~$82k, having struggled to regain momentum after the early-October pullback. Derivatives positioning has been similarly subdued. Aggregate BTC futures open interest currently sits around $52.9bn, broadly unchanged from last week. The absence of a material OI rebuild despite repeated moves through $80–84k suggests traders remain relatively reluctant to add directional leverage at current levels.
Perpetual funding has, however, firmed over the past several sessions. Notably, Binance’s daily average funding rate has risen from roughly 0.006% to 0.009% per eight hours over the past week. These are still orderly levels, but the direction is worth watching: longs are again paying to maintain exposure even though spot has made relatively little progress. Retail may be attempting to front-run the hype in other sectors, although the AI mania is reverting the other way.
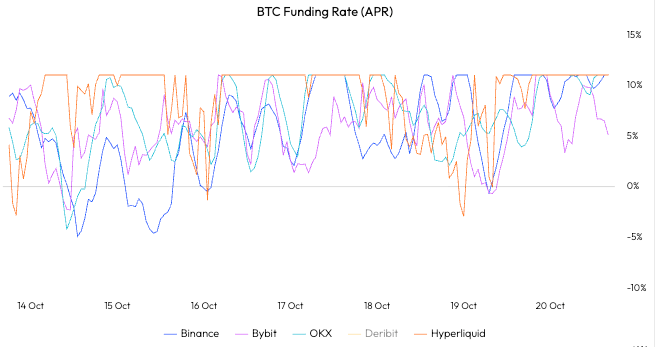
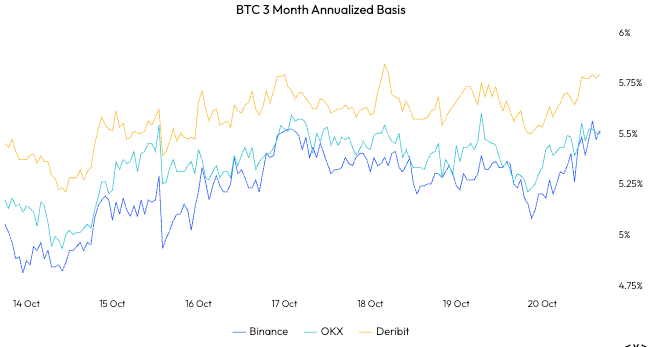
The dated futures curve remains constructive. The December BTC basis is broadly 5–6% annualised across the liquid venues. March 2027 basis is similarly clustered around 5.2–5.6%. The curve is remarkably flat across the medium-term maturities. Carry is positive, but there is still none of the aggressive curve steepening normally associated with a heavily levered directional market. The trend is encouraging though, despite the risk-free rate continuing its upward trajectory.
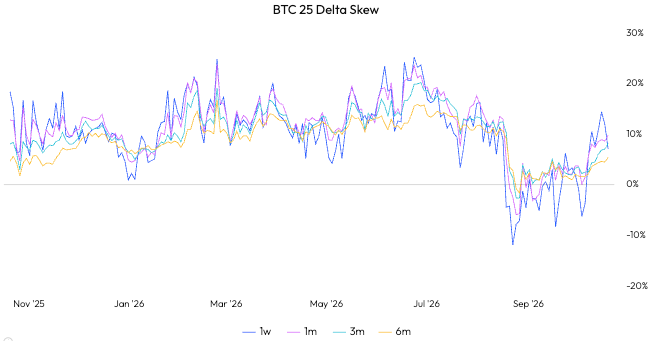
Options continue to tell a more defensive story. Over the week ending Friday, BTC 25-delta risk reversals moved further toward puts. The latest 1-week reading remains around -3.4 vols, meaning downside puts continue to trade at a meaningful volatility premium to equivalent calls. This extends the shift we highlighted last week: investors are willing to pay for downside protection even as outright leverage is still contained.
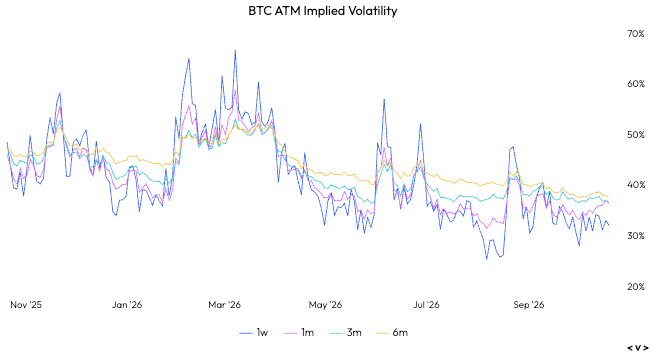
Outright volatility is still in the basement. One-week ATM implied volatility is around 32.7% versus seven-day realised volatility of 35.6%, while the listed October 30 expiry trades around 33–34% ATM, November around 36% and December around 37%. The curve remains upward sloping, with front-end implied volatility actually sitting below recent realised volatility. This is an important distinction: downside skew is expensive relative to calls, but absolute volatility itself is not particularly expensive.
The positioning into month-end is also worth watching. Deribit currently has approximately $32.4bn of BTC options open interest, with the 30 October expiry accounting for roughly $12.2bn, or close to 38% of the total. That expiry remains heavily call-weighted, with a put/call OI ratio around 0.51, even while the volatility surface prices puts richer than calls. In other words, the stock of outstanding positions remains skewed toward upside, while the marginal price of new protection is skewed toward downside.
Overall, the derivatives complex remains cautious rather than stressed. Futures OI is broadly flat, dated basis remains anchored around 5–6%, and funding has only recently moved back toward its conventional positive range. The clearer defensive signal is coming from the options surface, where investors continue to pay a premium for downside protection even though outright implied volatility remains relatively subdued.
Trade Idea: Principal Protected Notes
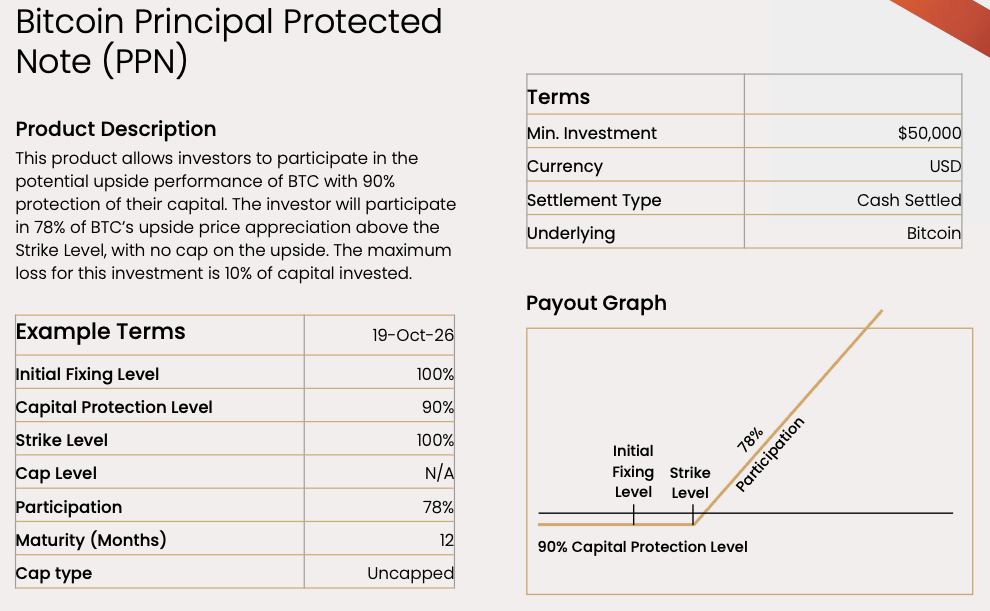
We’ve been getting some interest in PPN payoff structures. Not a bad trade given the current uncertainty: 90% principal protection at maturity, while retaining 78% participation in BTC upside above the initial fixing level, over a 12-month term.
With BTC implied volatility still relatively subdued, investors can currently access meaningful upside participation without taking full downside exposure.
Hit the team up if this is of interest!
Safe trading out there!
Jon de Wet, CIO
What to Watch
Tue: GB Unemployment Rate, US Building Permits
Wed: RBA Hauser Speech, GB Inflation Rate, JP Balance of Trade, US MBA 30-Year Mortgage Rate
Thu: ECB President Lagarde Speech, KR Interest Rate Decision
Fri: JP Inflation Rate
Contact Us
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
DISCLAIMER
Zerocap Pty Ltd carries out regulated and unregulated activities.
Spot crypto-asset services and products offered by Zerocap are not regulated by ASIC. Zerocap Pty Ltd is registered with AUSTRAC as a DCE (digital currency exchange) service provider (DCE100635539-001).
Regulated services and products include structured products (derivatives) and funds (managed investment schemes) are available to Wholesale Clients only as per Sections 761GA and 708(10) of the Corporations Act 2001 (Cth) (Sophisticated/Wholesale Client). To serve these products, Zerocap Pty Ltd is a Corporate Authorised Representative (CAR: 001289130) of AFSL 340799
This material is intended solely for the information of the particular person to whom it was provided by Zerocap and should not be relied upon by any other person. The information contained in this material is general in nature and does not constitute advice, take into account financial objectives or situation of an investor; nor a recommendation to deal. . Any recipients of this material acknowledge and agree that they must conduct and have conducted their own due diligence investigation and have not relied upon any representations of Zerocap, its officers, employees, representatives or associates. Zerocap has not independently verified the information contained in this material. Zerocap assumes no responsibility for updating any information, views or opinions contained in this material or for correcting any error or omission which may become apparent after the material has been issued. Zerocap does not give any warranty as to the accuracy, reliability or completeness of advice or information which is contained in this material. Except insofar as liability under any statute cannot be excluded, Zerocap and its officers, employees, representatives or associates do not accept any liability (whether arising in contract, in tort or negligence or otherwise) for any error or omission in this material or for any resulting loss or damage (whether direct, indirect, consequential or otherwise) suffered by the recipient of this material or any other person. This is a private communication and was not intended for public circulation or publication or for the use of any third party. This material must not be distributed or released in the United States. It may only be provided to persons who are outside the United States and are not acting for the account or benefit of, “US Persons” in connection with transactions that would be “offshore transactions” (as such terms are defined in Regulation S under the U.S. Securities Act of 1933, as amended (the “Securities Act”)). This material does not, and is not intended to, constitute an offer or invitation in the United States, or in any other place or jurisdiction in which, or to any person to whom, it would not be lawful to make such an offer or invitation. If you are not the intended recipient of this material, please notify Zerocap immediately and destroy all copies of this material, whether held in electronic or printed form or otherwise.
Disclosure of Interest: Zerocap, its officers, employees, representatives and associates within the meaning of Chapter 7 of the Corporations Act may receive commissions and management fees from transactions involving securities referred to in this material (which its representatives may directly share) and may from time to time hold interests in the assets referred to in this material. Investors should consider this material as only a single factor in making their investment decision.
Past performance is not indicative of future performance.
Like this article? Share
 Share
 Tweet
 Post

Latest Insights
Weekly Crypto Market Wrap: 12 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 5 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 28 September 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Receive Our Insights
Subscribe to receive our publications in newsletter format — the best way to stay informed about crypto asset market trends and topics.