


16 Nov, 26
Weekly Crypto Market Wrap: 16 November 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected] or visit our website www.zerocap.com
This is not financial advice. As always, do your own research.
Week in Review
- U.S. spot Bitcoin ETFs shed US$1.07B, their second consecutive week of billion-dollar outflows; Ethereum ETFs lost US$398.9M, extending their outflow streak to seven weeks.
- Bitcoin Core disclosed three previously patched security vulnerabilities, including a high-severity flaw that could disrupt block production for affected mining nodes.
- MARA posted a US$634M Q3 net profit; miner sold 13,597 BTC for US$1.1B, using US$750M to repay its Bitcoin-backed loans.
- Hyperliquid’s open interest grew nearly 80% in Q3 to a record US$16.8B, overtaking Bybit, Kraken and OKX; quarterly revenue rose 22% to US$191M.
- MSCI confirmed Strategy and Metaplanet will be removed from its indexes after the November 30 close, with JPMorgan estimating US$2.8B in passive selling of Strategy shares.
Technicals & Macro
Markets
Equities shook off a difficult few weeks and rallied, even as the inflation data argued the other way. The S&P 500 rose 2.5% to 7,561.67, the Nasdaq 2.3% and the Dow 2.1%, with all eleven sectors higher and the S&P snapping a four-week losing streak with its best week since August. Dip-buying drove much of it, with the largest S&P 500 ETF taking in close to US$17 billion over five sessions.
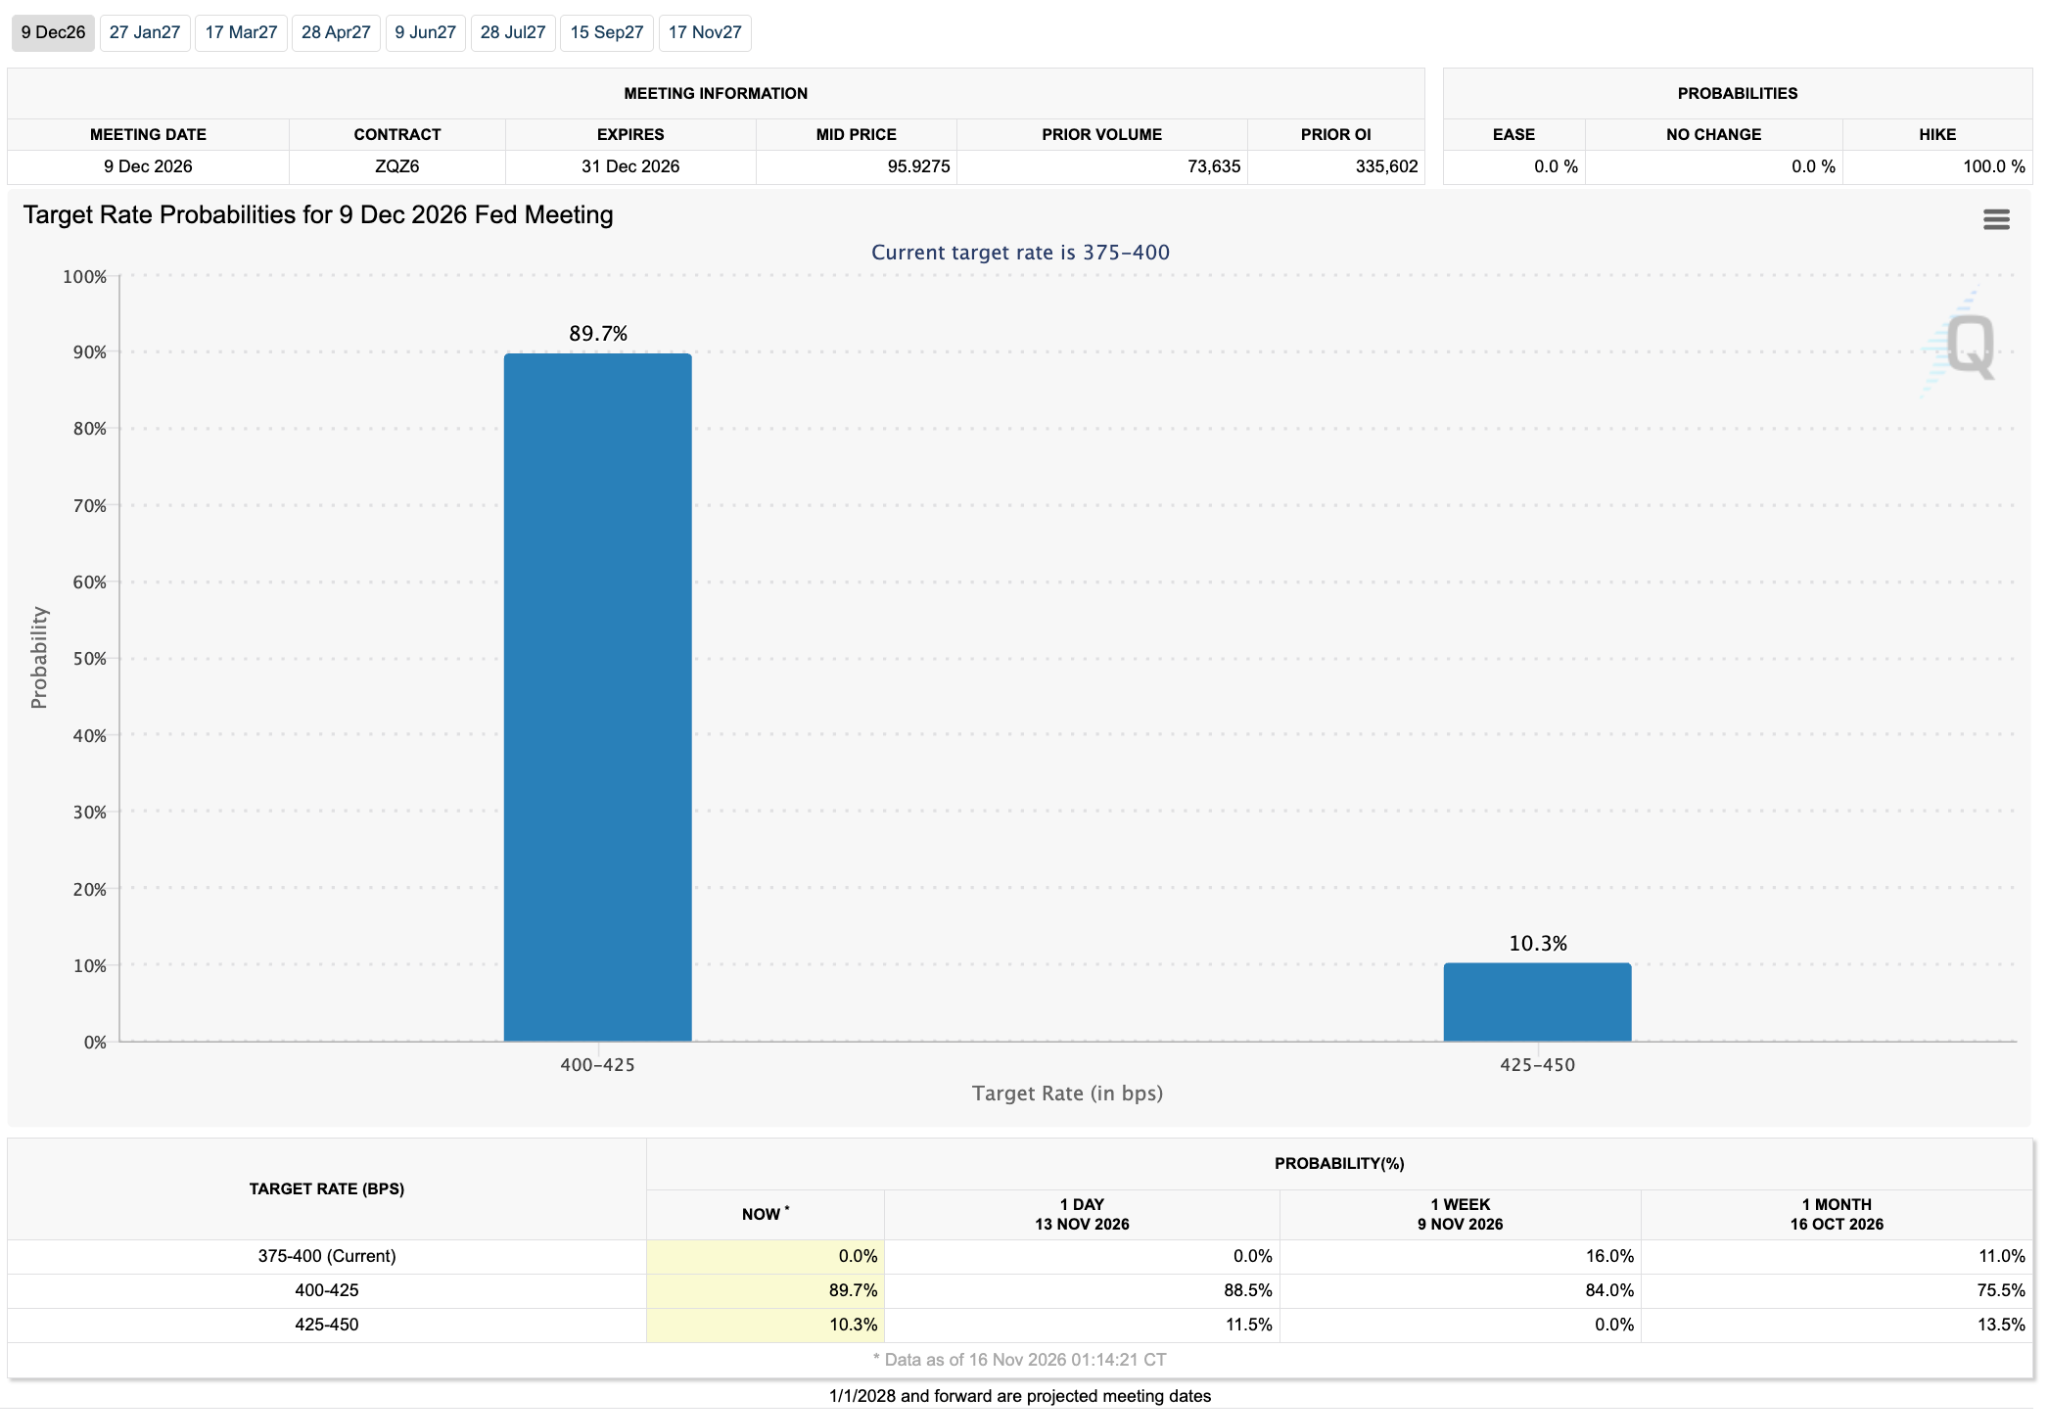
Source: FedWatch
The inflation data gave no support to that optimism. October CPI rose 0.4% on the month against expectations of 0.3%, and core rose 0.3% against 0.2%. Producer prices are up 6.5% on the year, the most since late 2022. Fed Governor Waller had said before the release that a core reading around 0.3% would put a 50 basis point hike on the table, and the print landed right on that line. A December hike is now fully priced, and the open question is size. The dollar index pushed above 103 to a 19-month high.
The AI trade took a hit on Thursday. Nvidia CEO Jensen Huang resigned with immediate effect, following reports of personal relationships including one with a customer alleged to be a Chinese intelligence asset. CFO Colette Kress is interim CEO. The stock fell as much as 16% before closing down 4.3%, and Bernstein halved its price target. Nvidia reports on Tuesday, and the result will be the first real read on whether the business, rather than the leadership story, is driving the stock.
Cryptocurrency
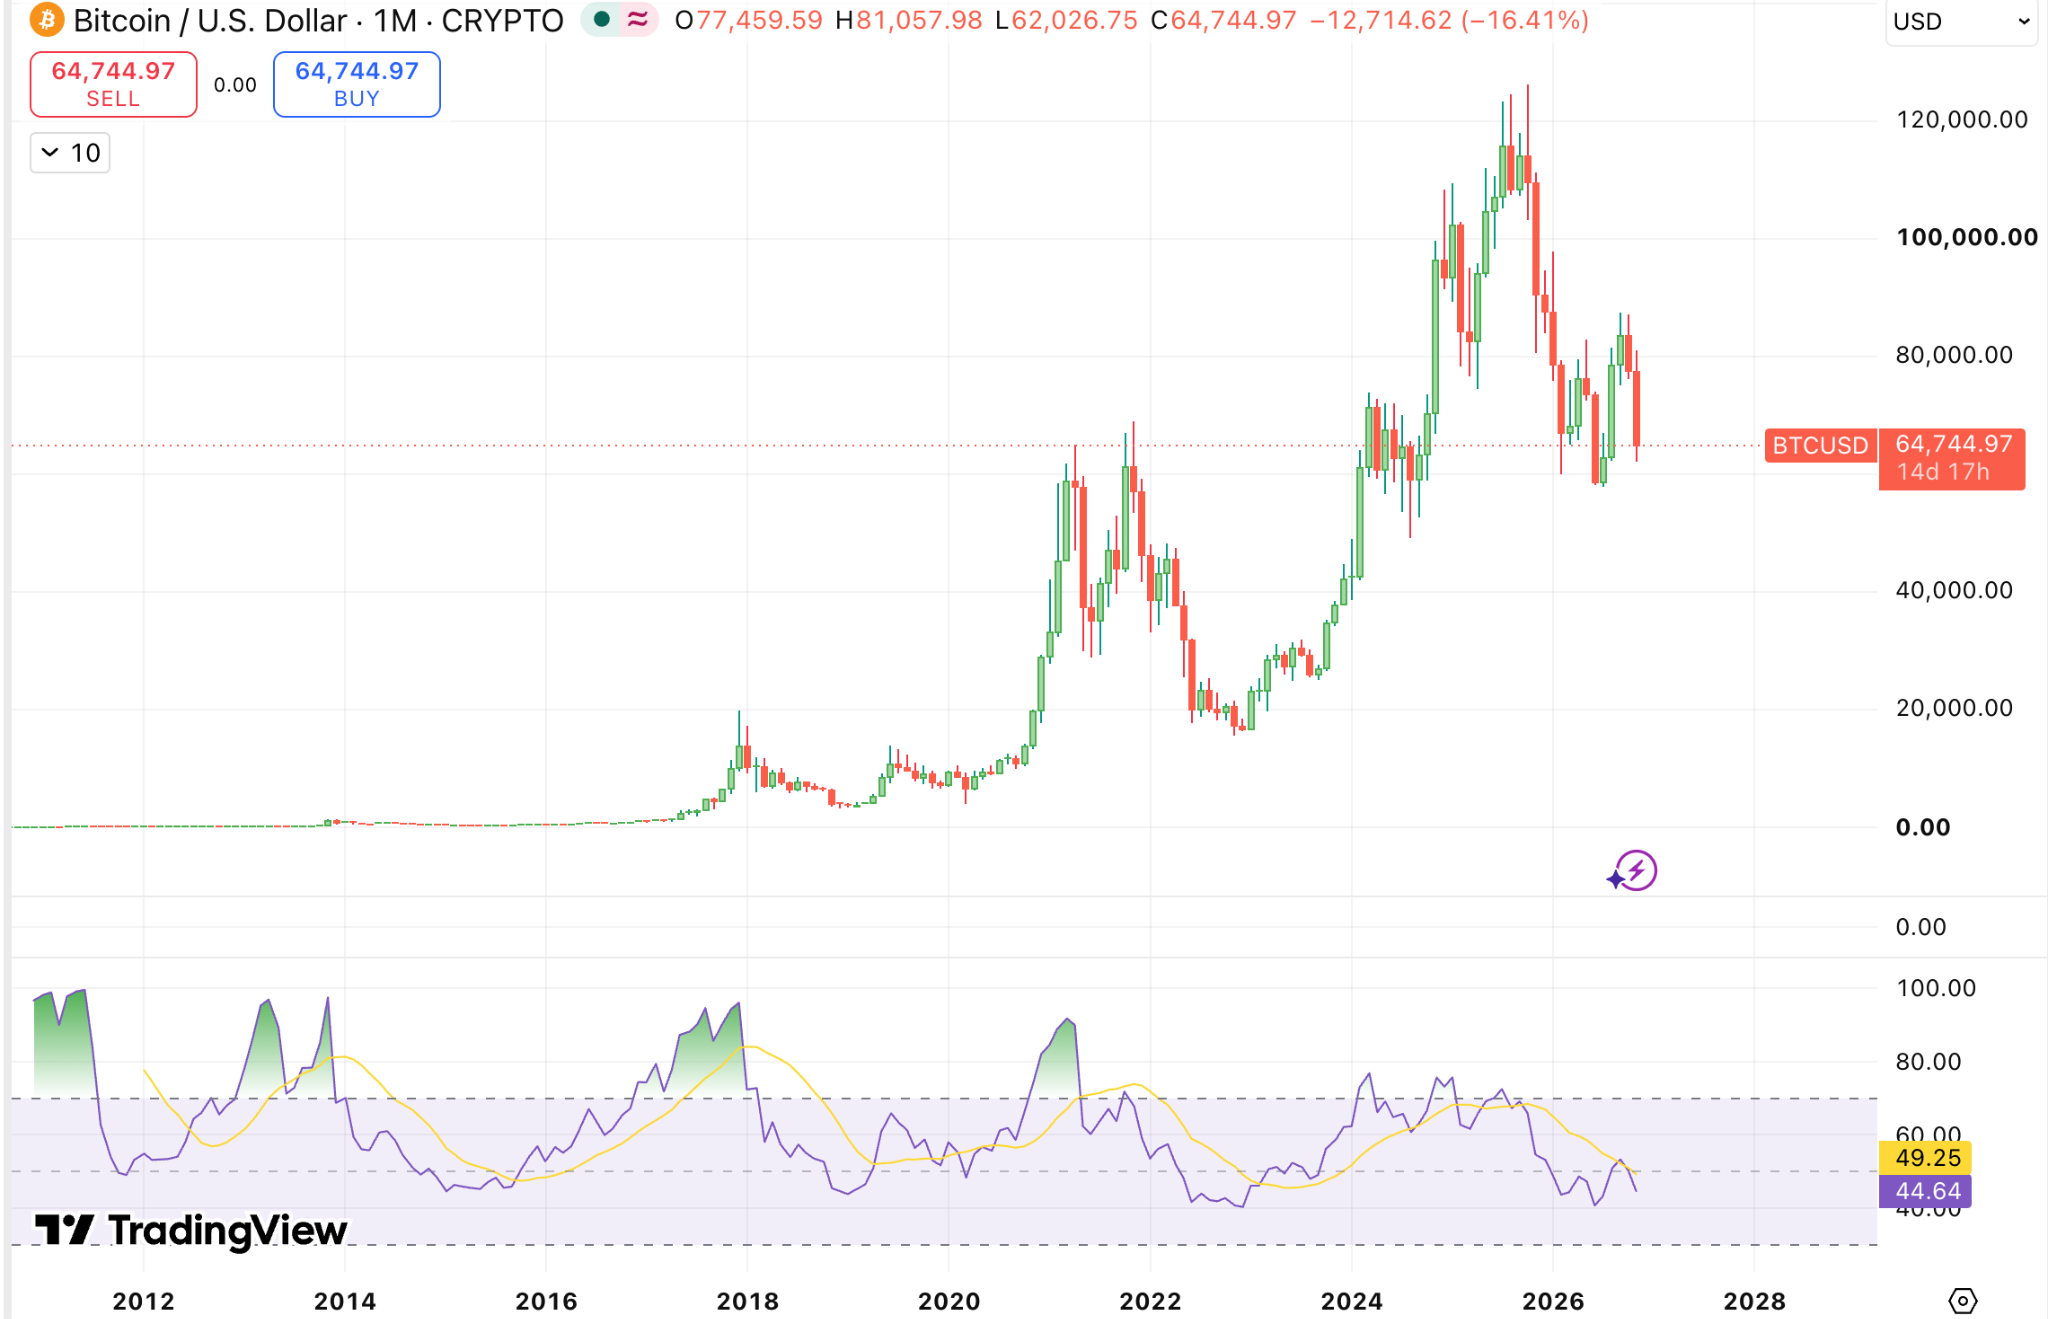
Source: TradingView
Bitcoin broke US$72,000 after the CPI print, broke US$70,000 on Friday, and kept falling to around US$62,100 over the weekend. It trades near US$64,538 this morning, down about 14% on the week and at its lowest since July. Ether is down around 15% at US$1,813.
The macro pressure was clear: a hot CPI, a dollar at a 19-month high and a fully priced Fed hike. What turned a decline into a flush was positioning. Leveraged longs were clustered just below US$70,000, and around US$2 billion was liquidated as that level gave way. Liquidity was already thin, with Talos estimating Bitcoin order-book depth on 9 November about a third below normal. Spot ETFs lost a further US$1.07 billion over the week, the seventh straight day of outflows, taking November’s total above US$2.3 billion. Part of that is the cash-and-carry trade unwinding: with the futures basis now below funding costs, hedge funds that held ETF shares against short futures have been exiting. Crypto and equities have now separated in the wrong direction. Stocks bounced on dip-buying while Bitcoin kept falling, which tells us the selling is coming from within crypto rather than following the broader risk tape.
The MSCI decision landed as expected. Strategy and Metaplanet will be removed from MSCI’s indexes after the 30 November close, with SharpLink placed on a watchlist. JPMorgan has estimated the passive selling of Strategy shares at around US$2.8 billion, and up to US$8.8 billion if other index providers follow. Strategy’s position is now well below its average cost of about US$75,450. It holds no pledged Bitcoin and keeps around US$4.8 billion in reserves, so there is no forced selling of the coin. But its ability to raise fresh capital, which has been a steady source of demand all year, is now clearly impaired.
Sentiment has reached an extreme, with the Fear and Greed index at 13. Some on-chain analysts argue Bitcoin has entered a historically meaningful valuation zone, with many recent sellers being buyers from above US$80,000. That may prove right over months, but it is not a reason to expect a quick recovery while ETF outflows continue.
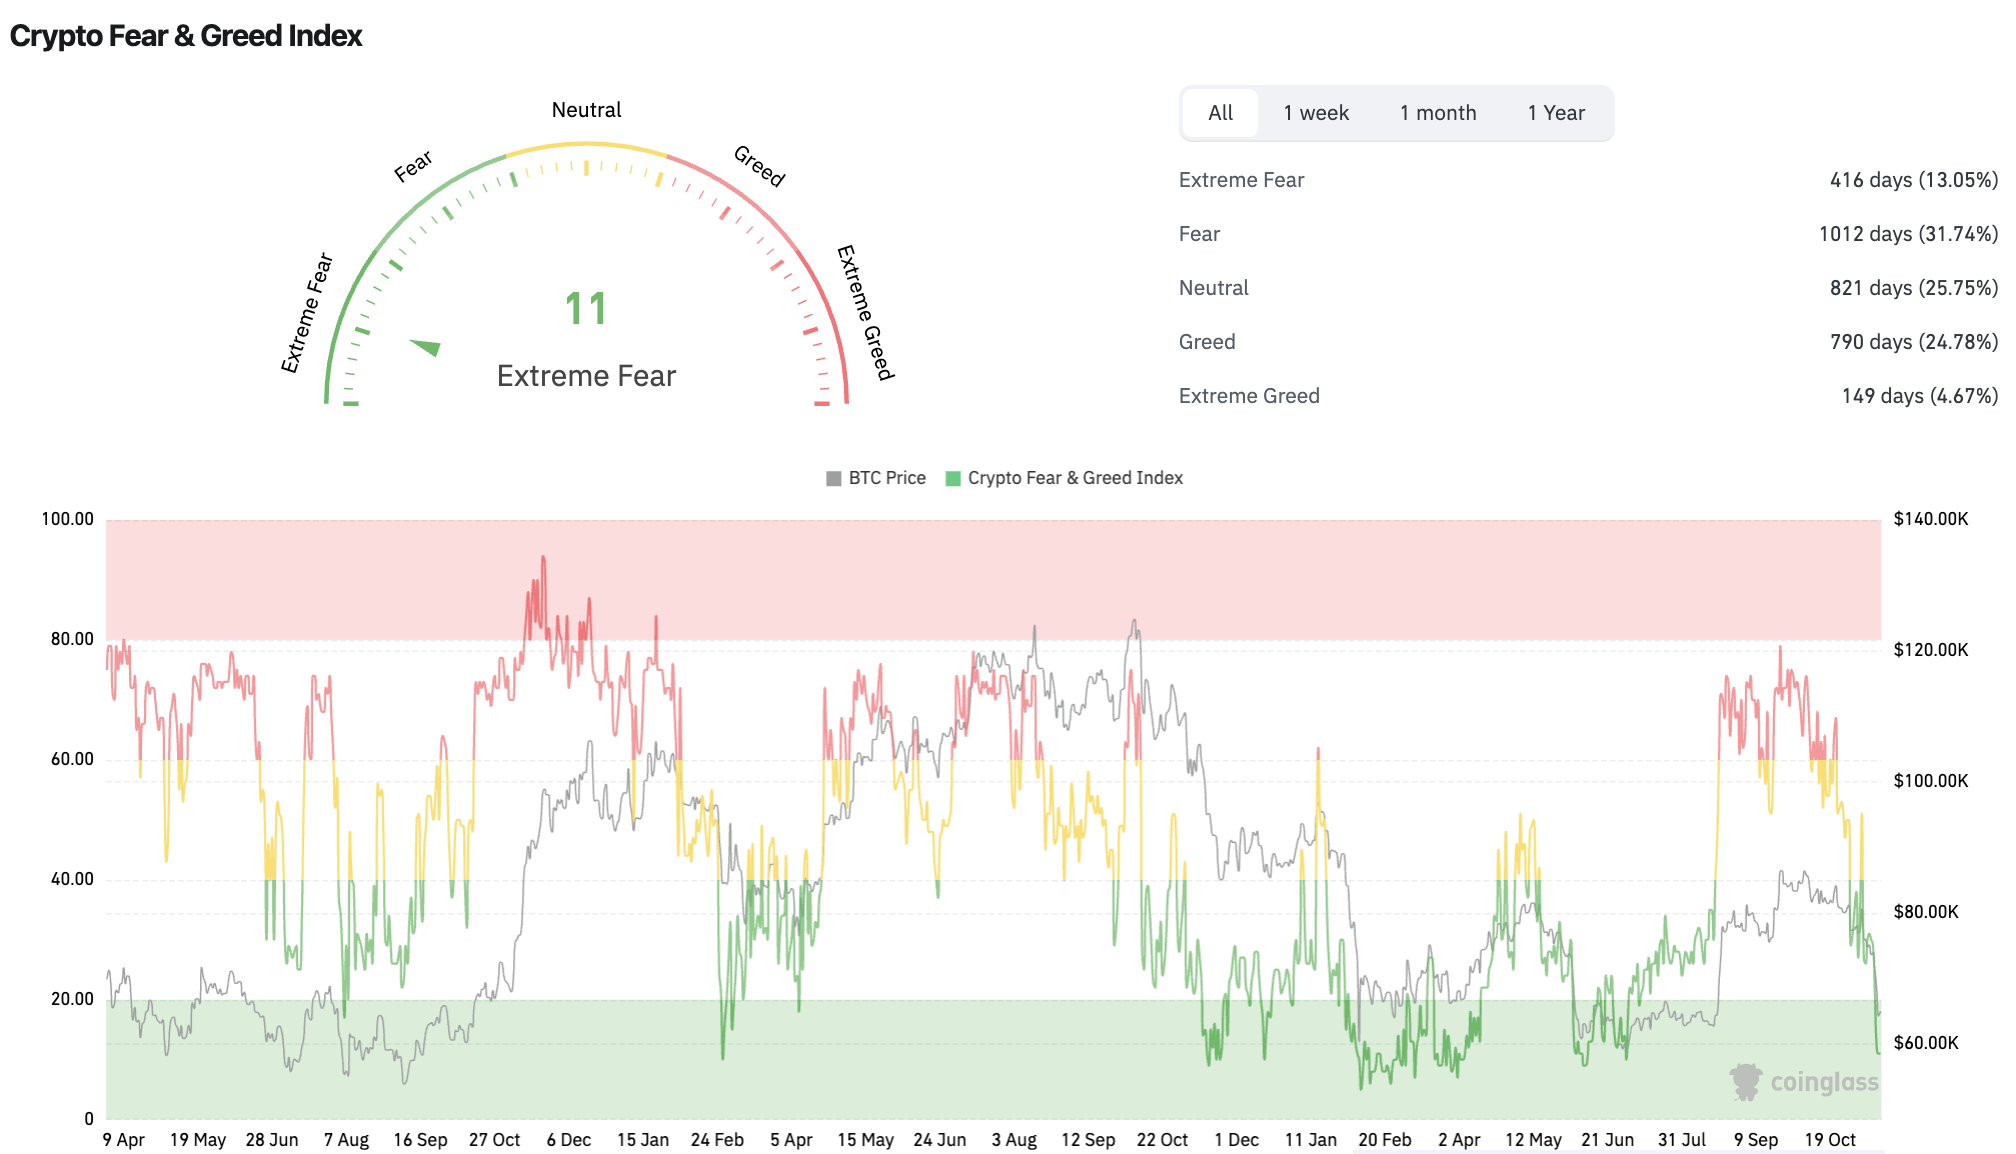
Source: CoinGlass
Our call for next week: We expect US$60,000 to hold, supported by the speed of the move, and how much leverage has already been cleared. The 200-week average near US$67,800 is now resistance, and a daily close back above it would be the first sign the flush is done. A close below US$60,000 opens a retest of the July low at US$58,570. Nvidia’s results on Tuesday are the most likely catalyst either way.
For any pricing needs, please get in touch.
Emir Ibrahim
Spot Desk
Digital assets endured a week of historic selling pressure as Bitcoin (BTC) fell from US$74,851 to close at US$65,351, after trading as low as US$62,006 and repricing into the lower end of the US$60k–83k range that has broadly defined price action on the year. Institutional sponsorship weakened further as BTC ETF redemptions continued, while ETH products recorded US$398.9M of outflows, marking a seventh consecutive negative week; corporate balance-sheet activity added to the headwinds, with MARA selling 13,597 BTC for approximately US$1.1B and using US$750M of the proceeds to fully repay its bitcoin-collateralised loans.
Desk activity ran counter to the broader tape: BTC and ETH were both net bought as clients accumulated into weakness despite deteriorating price action and persistent ETF redemptions, with relatively heightened weekend trading activity as selling intensified in the broader market, with a persistent spot supply fed through Coinbase into thinner liquidity and helping push BTC toward the weekly lows. Further out the curve, risk reduction was more evident, with clients consolidating smaller long-tail positions such as Polkadot (DOT) back into fiat. Solana (SOL) was net bought in connection with ETF creation activity-related flows.
Stablecoins accounted for a significant share of desk turnover, with both USDT and USDC seeing notable net off-ramping and persistent secondary market discounts. A reversal in USDC flow was notable, marking its first meaningful off-ramping week in some time after remaining consistently bid through much of the year; this shift likely reflects heightened demand for operational USD liquidity amid softer trade. AUDD continued to see strong use as an on-ramping fiat alternative rail.
In FX, AUD/USD traded heavily, falling from 0.6863 to 0.6767 as broad risk aversion and haven demand pushed DXY to fresh 19-month highs and the rates backdrop also turned decisively less supportive. A hotter-than-expected US CPI print moved a December Fed hike to near fully-priced, shifting the debate from timing toward the likely size of the move, while US 10-year yields climbed back to 5.14%. Domestically, market-priced probability of another RBA hike is now close to zero following November’s “dovish hike” and the Board’s signal that it intends to “take stock.” Through much of the year, a hawkish RBA relative to a Fed on hold supported AUD; that divergence has now reversed, with US policy expectations tightening as the domestic cycle appears to be plateauing. The resulting deterioration in the yield differential, combined with AUD’s high-beta sensitivity to global risk, leaves the currency facing a materially less supportive backdrop. In flows, clients used the relative pair weakness to accumulate, with AUD finishing net bid alongside NZD, while EUR and GBP were sold.
The OTC desk continues to provide tailored cryptocurrency liquidity solutions and competitive pricing across major digital assets, stablecoins, selected altcoins and key fiat currency pairs. With T+0 settlement capability, the desk continues to facilitate efficient execution and settlement across client flows.
Ben Mensah, OTC Trader
Derivatives Desk
WHOLESALE INVESTORS ONLY
BTC has had another brutal week, falling roughly 14% over seven days and trading around $64–65k, after briefly printing near $62k over the weekend. Spot demand remains a major headwind with US spot ETFs experiencing net outflows across seven consecutive outflow sessions.
The sell-off has produced meaningful reduction in leverage. Aggregate BTC futures open interest is currently approximately $18bn, versus roughly $22bn across the major exchanges a week ago — an almost 19% decline in USD terms. Some caution is required when interpreting that number because BTC itself has fallen materially, mechanically reducing the dollar value of outstanding positions. Even adjusting approximately for the change in spot, however, open exposure has declined, consistent with genuine deleveraging rather than purely mark-to-market effects.
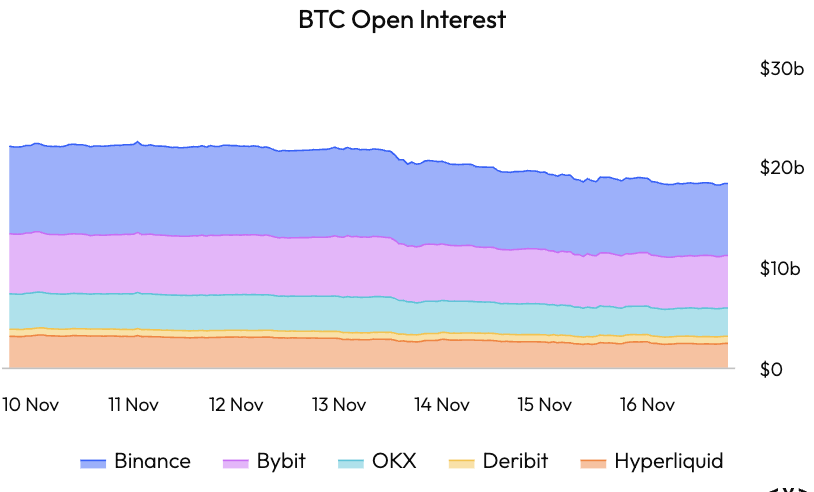
Source: Velodata
That deleveraging was concentrated late in the week. Liqwall estimates that $643m of BTC positions were liquidated on 13 November and another $629m on 14 November, with longs representing approximately $1.18bn of the $1.27bn combined total. The broader crypto market saw roughly $1.54bn of liquidations on 14 November alone, 94% of which were longs. This was a genuine long-side flush.
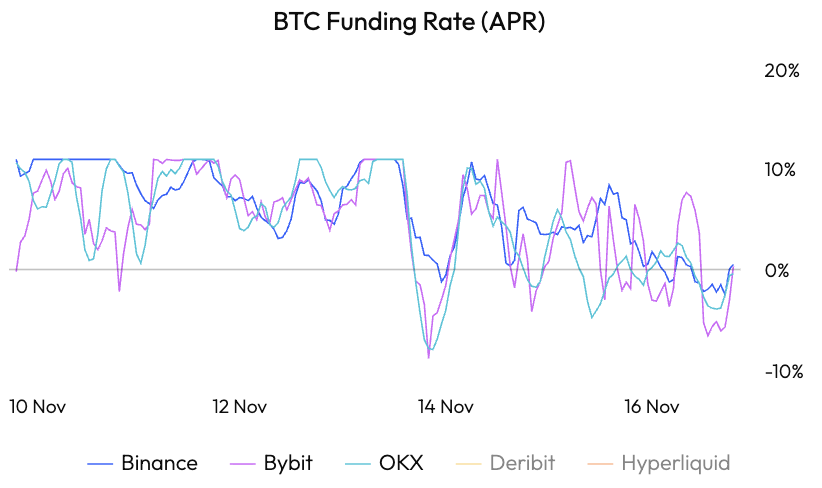
Funding has responded accordingly. The perpetual market is now effectively flat to slightly negative, a substantial change from earlier this month. Leveraged longs are no longer paying a meaningful premium to remain in the market. As they say, don’t catch the falling knife, but price action does not like we have a reasonably stable base.. for now.
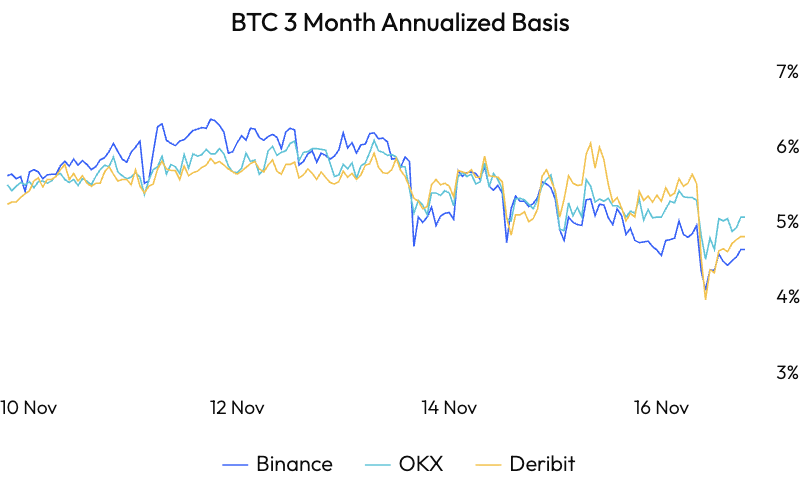
Interestingly, the dated futures curve has remained relatively resilient, despite the drop – and as I write we are normalising back into the 5% range.
The most dramatic repricing remains in options. One-week ATM implied volatility is now 48.35%, versus 40.89% at one month and approximately 40% from three to nine months. The front of the curve is therefore heavily inverted, with 1-week IV trading around 7.5 volatility points above 1-month. Only two days earlier, one-week IV had been around 36%, illustrating how aggressively near-term uncertainty has been repriced as spot broke lower. BTC Dvol tells the vol story – boom and bust.
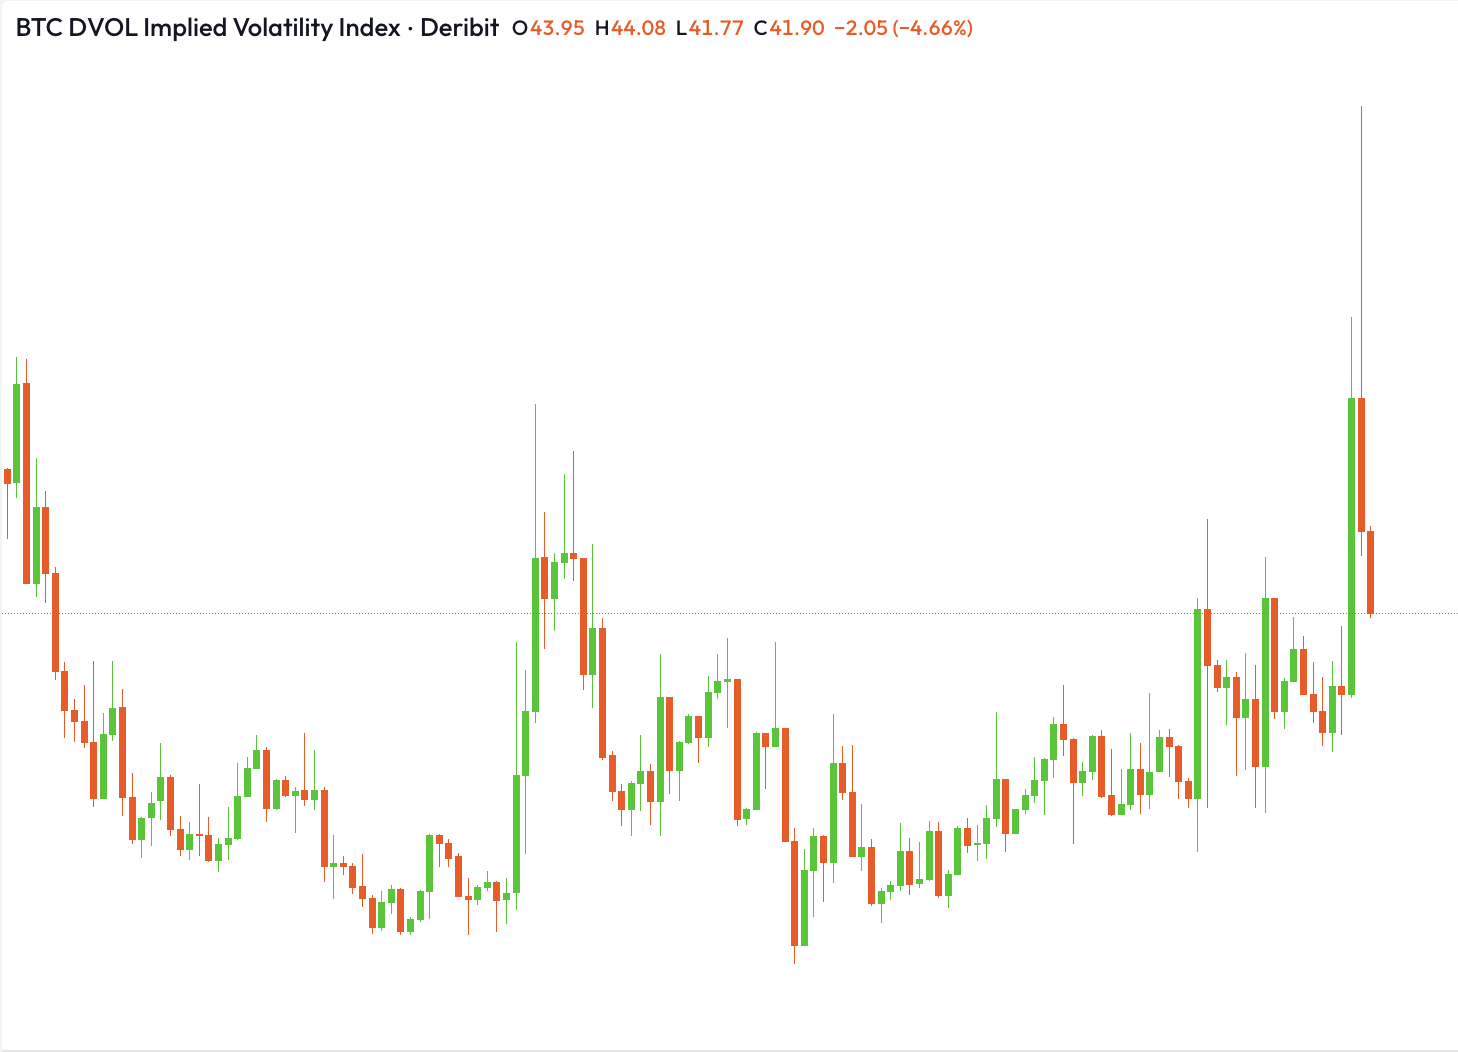
But there is an important nuance: despite IV looking optically high, realised volatility has been even higher. Trailing seven-day realised volatility is approximately 58.3%, almost 10 volatility points above current one-week implied. So we would be careful describing outright options as expensive simply because IV has jumped. BTC has actually been moving more violently than the option market is currently implying. Vol carry strategies would be feeling the pain here.
Overall, the derivatives complex has finally moved from “defensive but leveraged” to genuinely deleveraged. Open interest has contracted, funding has reset toward zero, and more than $1bn of BTC longs were liquidated across Thursday and Friday. Yet dated basis remains around the mid-single digits and longer-dated implied volatility remains anchored close to 40%. The stress is therefore highly concentrated in spot, front-end volatility and downside skew, rather than across the entire derivatives curve.
Safe trading out there!
Jon de Wet, CIO
What to Watch
Mon: CN Unemployment Rate, BoJ Takada Speech
Tue: Fed Chair Warsh Speech, GB Unemployment Rate, RBA Meeting Minutes
Wed: RBA Gov Bullock Speech, US Retail Sales MoM
Thu: AU Unemployment Rate, ECB President Lagarde Speech, FOMC Minutes
Fri: JP Inflation Rate YoY
Disclaimer
This material is issued by Zerocap Pty Ltd (Zerocap), a Corporate Authorised Representative (CAR: 001289130) of Gannet Capital Pty Ltd (GC) AFSL 340799.
Material covering regulated financial products is issued to you on the basis that you qualify as a “Wholesale Investor” for the purposes of Sections 761GA and 708(10) of the Corporations Act 2001 (Cth) (Sophisticated/Wholesale Client), or your local equivalent.
This material is intended solely for the information of the particular person to whom it was provided by Zerocap and should not be relied upon by any other person. The information contained in this material is general in nature and does not constitute advice, take into account financial objectives or situation of an investor; nor a recommendation to deal. Any recipients of this material acknowledge and agree that they must conduct and have conducted their own due diligence investigation and have not relied upon any representations of Zerocap, its officers, employees, representatives or associates. Zerocap has not independently verified the information contained in this material. Zerocap assumes no responsibility for updating any information, views or opinions contained in this material or for correcting any error or omission which may become apparent after the material has been issued. Zerocap does not give any warranty as to the accuracy, reliability or completeness of advice or information which is contained in this material. Except insofar as liability under any statute cannot be excluded, Zerocap and its officers, employees, representatives or associates do not accept any liability (whether arising in contract, in tort or negligence or otherwise) for any error or omission in this material or for any resulting loss or damage (whether direct, indirect, consequential or otherwise) suffered by the recipient of this material or any other person. This is a private communication and was not intended for public circulation or publication or for the use of any third party. This material must not be distributed or released in the United States. It may only be provided to persons who are outside the United States and are not acting for the account or benefit of, “US Persons” in connection with transactions that would be “offshore transactions” (as such terms are defined in Regulation S under the U.S. Securities Act of 1933, as amended (the “Securities Act”)). This material does not, and is not intended to, constitute an offer or invitation in the United States, or in any other place or jurisdiction in which, or to any person to whom, it would not be lawful to make such an offer or invitation. If you are not the intended recipient of this material, please notify Zerocap immediately and destroy all copies of this material, whether held in electronic or printed form or otherwise.
Disclosure of Interest: Zerocap, its officers, employees, representatives and associates within the meaning of Chapter 7 of the Corporations Act may receive commissions and management fees from transactions involving securities referred to in this material (which its representatives may directly share) and may from time to time hold interests in the assets referred to in this material. Investors should consider this material as only a single factor in making their investment decision.
Contact Us
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
Like this article? Share
 Share
 Tweet
 Post

Latest Insights
Weekly Crypto Market Wrap: 9 November 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 4 November 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 26 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Receive Our Insights
Subscribe to receive our publications in newsletter format — the best way to stay informed about crypto asset market trends and topics.