


5 Nov, 26
Weekly Crypto Market Wrap: 4 November 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
This is not financial advice. As always, do your own research.
Week in Review
- Binance suffers a record US$6.3B security breach; exchange has since replenished ~95% of affected assets and re-enabled withdrawals after temporary suspension.
- U.S. spot Bitcoin ETFs shed US$202.6M as heavy Friday redemptions erased earlier inflows; Ethereum ETFs lost US$431.5M amid sustained selling pressure.
- NYSE parent ICE and Stanley Druckenmiller partner with TradeXYZ to develop U.S. perpetual futures markets built on Hyperliquid infrastructure.
- CFTC approves single-stock perpetual futures trading in the U.S. for the first time, opening a new chapter for domestic derivatives markets.
- RBA lifts cash rate 25bps to 4.85% in a split 6–3 decision, with economists anticipating a potential pause in December.
Technicals & Macro
Markets
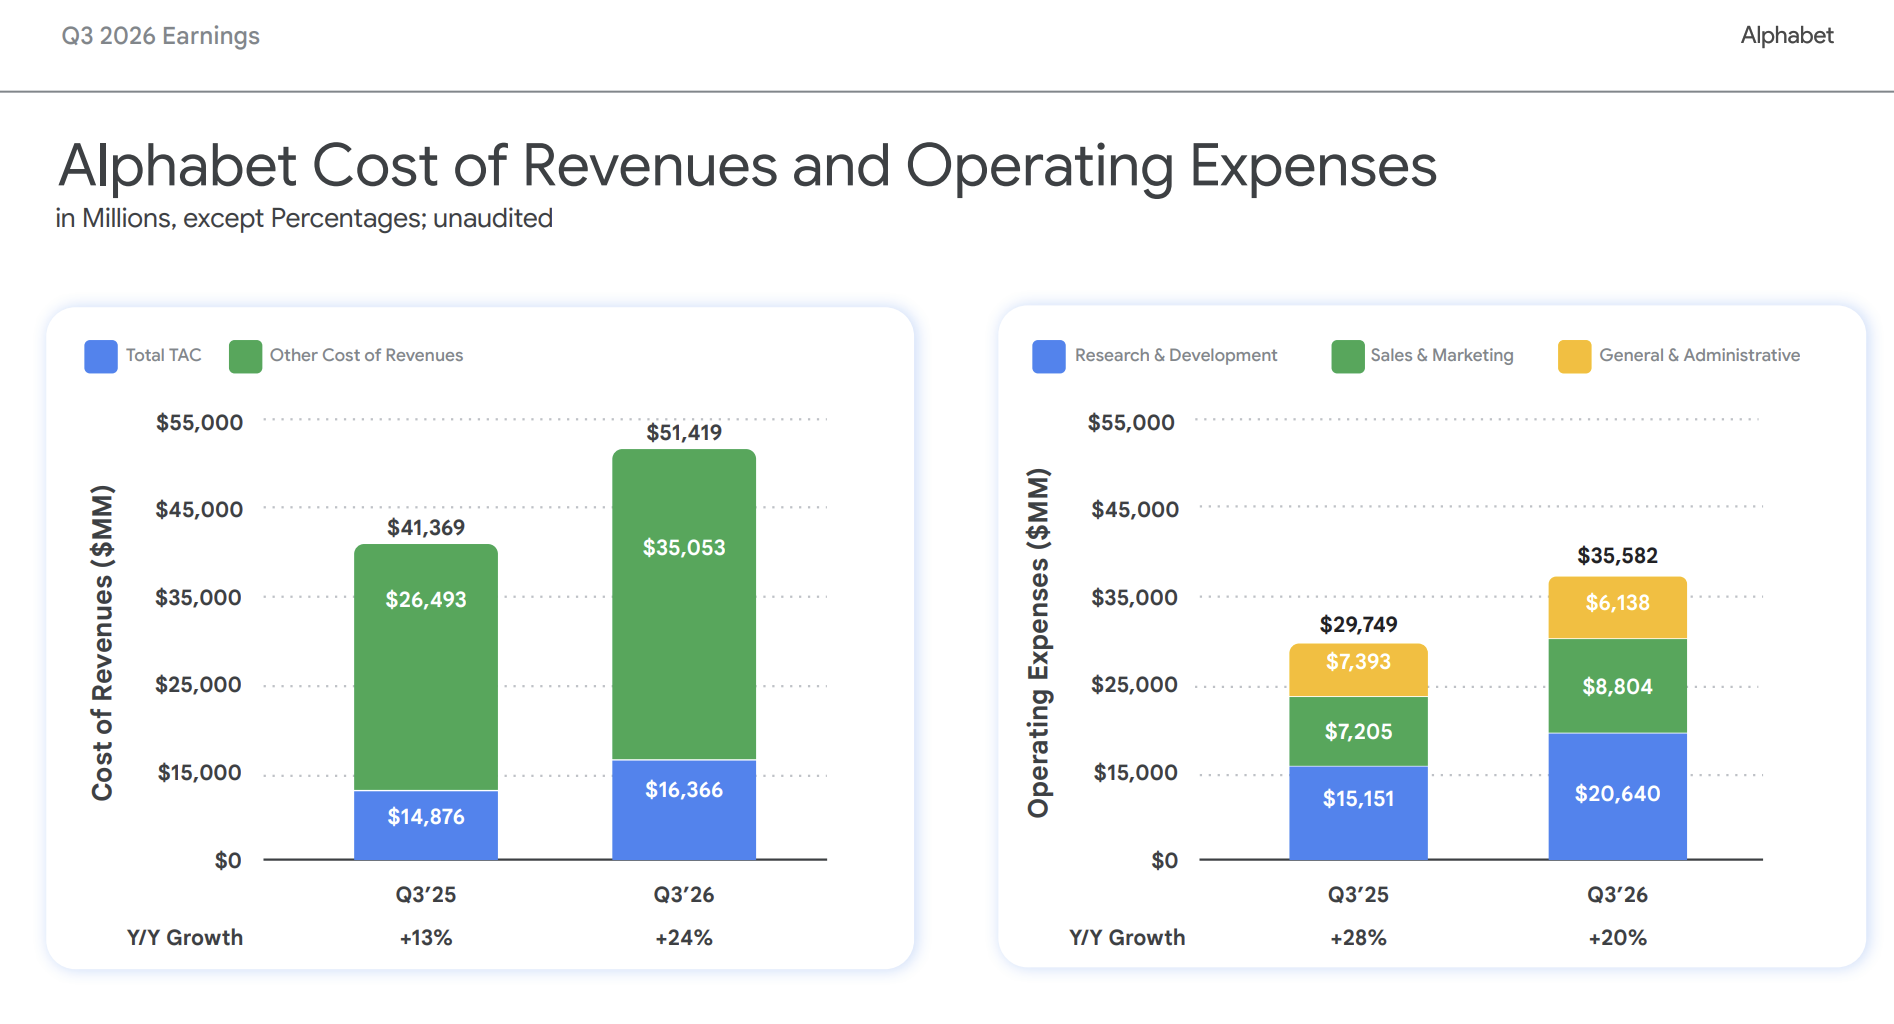
The AI trade is now being priced on cash, not growth. Alphabet fell 12.6 percent on 29 October, its worst day as a public company, after reporting negative free cash flow of US$9.1 billion as capex outran operating cash. Intel followed with a 28.6 percent fall, its worst session since 1974, and Amazon disappointed on both profit and spending. Microsoft was the exception. It produced US$18.6 billion of positive free cash flow and barely moved. Investors will still pay for AI, but only from companies that can fund it.
That left the Nasdaq down 5.3 percent for October, its worst month since March 2025, and 2.9 percent lower on Friday alone. The damage stayed concentrated. Small caps rose 1.3 percent on the week and the equal-weight S&P 500 outperformed the headline index for a fourth straight week. Stocks steadied on Tuesday, with the S&P 500 up 0.4 percent to 7,568.92, breaking a three-day losing run as chips bounced into the midterms.
The Fed held at 3.75 to 4.00 percent on 28 October, with Cleveland’s Hammack and Governor Cook both dissenting in favour of a hike. Chair Warsh again gave no guidance on the December decision, but markets read the dissents clearly and now price around an 83 percent chance of a hike on 9 December. He also announced that from 2027 one of the Fed’s eight meetings will be set aside for strategy, with no rate decision. The 10-year eased to around 4.93 percent as money moved out of tech and into bonds.
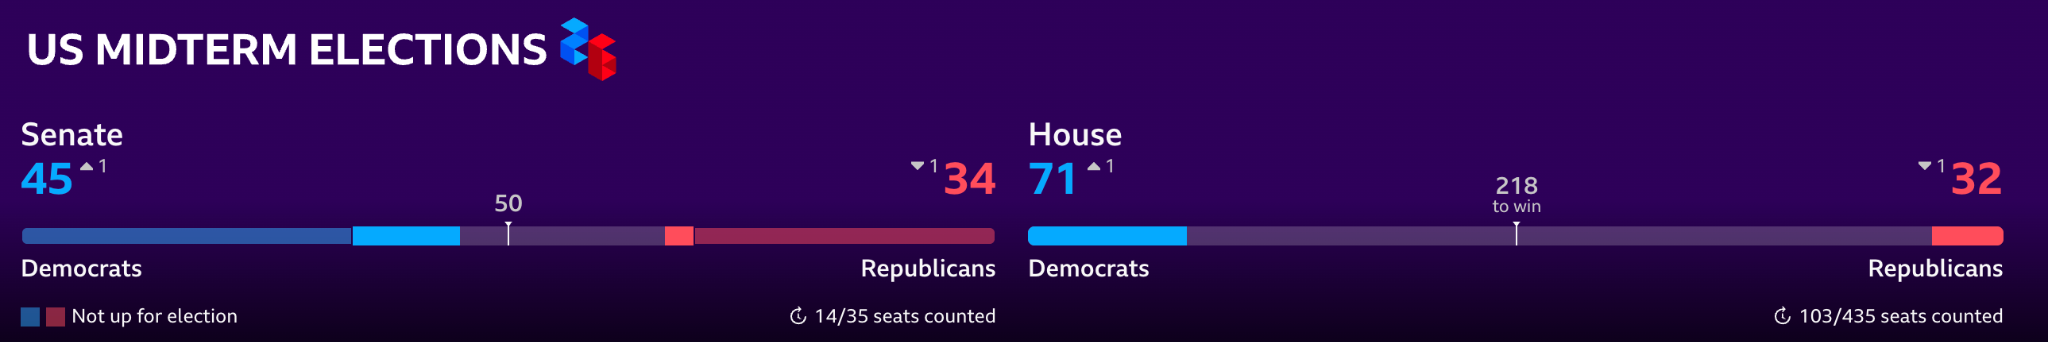
The US midterm count is still running. Democrats are favoured to take the House and have flipped North Carolina’s Senate seat, but the Senate remains too close to call. Strategists had warned that a Democratic sweep is not fully priced, and if it materialises the pressure is likely to fall hardest on the AI names already under strain. Friday’s payrolls report is the next major input for the Fed.
Cryptocurrency
Last week we said a daily close below US$80,000 would open a move to US$76,000 to US$77,000. That is where we are. But the catalyst wasn’t the Fed. It was Binance.
On the evening of 29 October, the world’s largest exchange lost around US$6.3 billion in what is now the largest crypto theft on record, behind last year’s Bybit hack. Binance froze withdrawals, partners helped freeze around US$3 billion of the stolen funds, and the exchange says it has replaced roughly 95 percent of affected assets from its own balance sheet without borrowing or selling. Bitcoin fell to around US$76,170 on Friday, its lowest since mid-September, as close to US$1.6 billion of positions were liquidated, mostly longs. BNB fell 7.6 percent on Thursday.
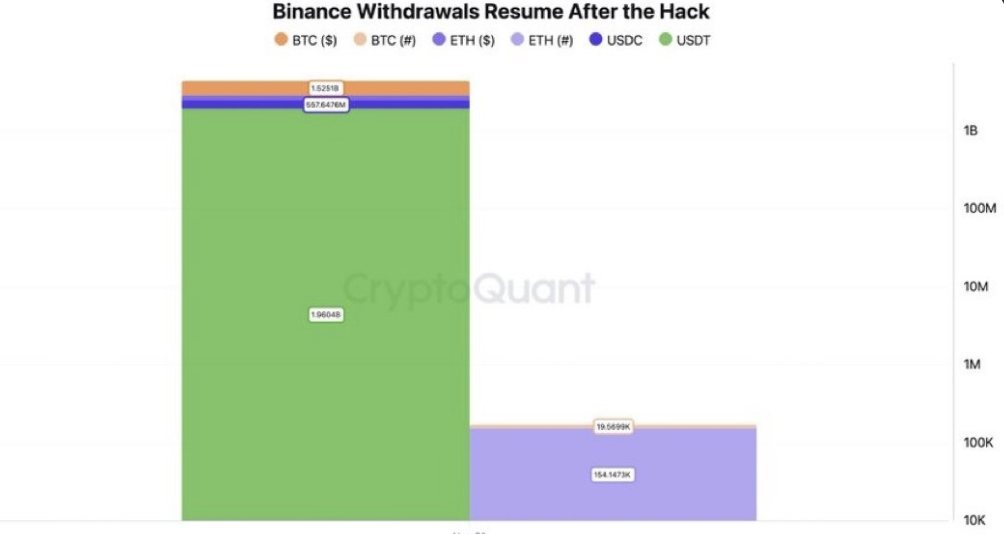
The more important number came after withdrawals reopened on Sunday. Net outflows on day one were about US$3.6 billion, roughly 3.6 percent of the US$171 billion Binance held before the attack. That is a meaningful exit but not a run, and it suggests the balance sheet response has held confidence for now. The risk is a slower second wave if users who waited decide to move once all assets and networks are restored.
On the same day as the hack, the opposite signal came from traditional finance. ICE, the owner of the New York Stock Exchange, agreed to become the exclusive operator of Trade[XYZ]’s regulated markets and took a minority stake in the company. Trade[XYZ] runs perpetual futures on stocks, commodities, FX and crypto on Hyperliquid, and claims more than US$650 billion of volume in just over a year. ICE would build a dedicated US exchange and clearing structure on that infrastructure, with access through registered futures brokers and distribution through its joint venture with OKX. Stanley Druckenmiller disclosed a personal stake in Trade[XYZ] the same day, and HYPE jumped as much as 17 percent.
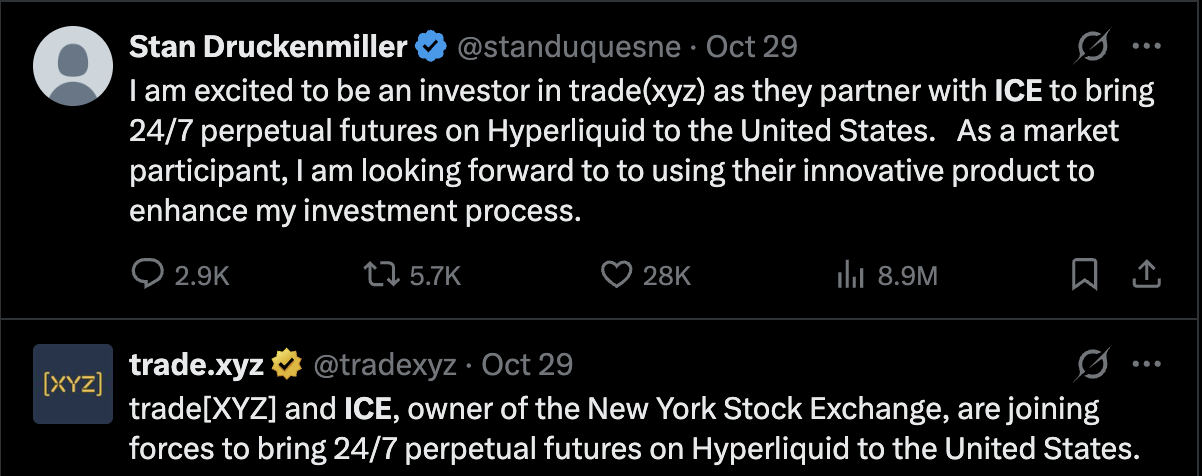
The reversal is striking. In May, ICE and CME were pressing regulators to scrutinise Hyperliquid over manipulation and sanctions risk. Now ICE is building on it. Two qualifications matter. Nothing launches until the CFTC approves it, and ICE has already reposted its announcement to make that clear. And ICE’s investment is in Trade[XYZ], not HYPE. Hyperliquid’s founder has also been explicit that compliance sits with the operators above the protocol, not the protocol itself. Still, this is the first serious test of a regulated onshore path for perpetual futures, and the template it sets will matter well beyond Hyperliquid.
Our call for next week: We think the forced selling from the hack has largely cleared, and expect US$75,000 to hold. Getting back above US$80,000 needs ETF inflows to return and a payrolls print that doesn’t harden December. A daily close below US$75,000 would open a move toward US$72,000 to US$73,000. Not financial advice!
For any pricing needs, please get in touch.
Emir Ibrahim
Spot Desk
Digital assets held up with reasonable relative strength through a week of significant de-grossing across risk, as the AI trade unwind drove a sharp repricing through the technology complex. Rather than trading as a one-for-one high-beta extension of equities, majors drifted around established range lows without an impulsive breakdown, and realised volatility remained relatively muted against the sharper repricing in equities; potentially indicative of a market that has already seen the bulk of its derisking. That said, institutional sponsorship was notably weaker: BTC ETFs shed roughly US$202M on the week, as Friday’s US$643M redemption more than offset four sessions of inflows, while ETH products recorded US$431M of outflows in a more persistent daily fashion.
Desk activity broadly reflected the softened risk appetite: BTC carried a net selling skew in line with the weaker passive channel, while ETH was net bought in modest size as desk flows ran countertrend to both softer price action and sustained ETF redemptions. Further out the curve, XRP saw elevated two-way activity that resolved into a net selling skew, with long-tail participation beyond this otherwise minimal.
Stablecoin interests continued to dominate desk turnover: USDT was significantly net sold as the risk-off backdrop reinforced demand for USD liquidity, even with secondary market pricing widening to some of its deepest discounts of the year. USDC was net bought in modest size, extending its recent divergence from USDT in a desk flow theme that has become persistent on the year.
In FX, AUD/USD finished last week broadly unchanged before selling off sharply following Tuesday’s RBA decision, falling from a weekly open at 0.7030 to currently 0.6954 – this move coming despite concurrent USD weakness around early US midterm results suggests the domestic rates impulse as the dominant driver. The RBA delivered the expected 25bp hike to 4.85%, but the 6–3 split, removal of explicit further-tightening language and Governor Bullock’s preference to “take stock” after five hikes produced a distinctly less-hawkish read-through. The updated forecasts reinforce a more balanced reaction function: medium-term growth was revised lower, unemployment is now expected to reach 5.1%, and the NAIRU estimate was lifted to 4.75%, even as inflation remains above target for longer. With the Board also tightening into a softening property market, markets are increasingly viewing the cash rate as near its cyclical peak as many participants label Tuesday’s move a “dovish hike”. For AUD, that reduces the marginal support from domestic policy and shifts the near-term focus back toward DXY, global risk sentiment and relative-rate repricing. AUD was net sold into stablecoins and digital assets as flows favoured on-ramping, with AUDD skewed the same way as it continues to function as a preferred local fiat rail alternative amongst clients. Elsewhere, EUR was offered while NZD and GBP were bought.
The OTC desk continues to provide tailored cryptocurrency liquidity solutions and competitive pricing across major digital assets, stablecoins, selected altcoins and key fiat currency pairs. With T+0 settlement capability, the desk continues to facilitate efficient execution and settlement across client flows.
Ben Mensah, OTC Trader
Derivatives Desk
WHOLESALE INVESTORS ONLY
The 29 October Binance hack pushed BTC sharply below $80k. This was compounded by a more hawkish macro backdrop: the Fed held rates at 3.75–4.00%, but two FOMC members dissented in favour of a 25bp hike. U.S. spot BTC ETFs have recorded net outflows across the three sessions from Friday through Tuesday, adding to pressure on spot demand.
Despite the move lower, the futures market has not experienced a wholesale leverage unwind. Aggregate BTC futures open interest remains around $52–53bn. On Tuesday, BTC futures OI declined approximately 1.2% while spot fell 1.23%, suggesting much of the reduction in dollar OI was consistent with the decline in the underlying rather than aggressive position closure. More broadly, futures volume has increased sharply through the volatility while OI has remained comparatively stable — more consistent with active risk transfer and hedging than a major deleveraging event.
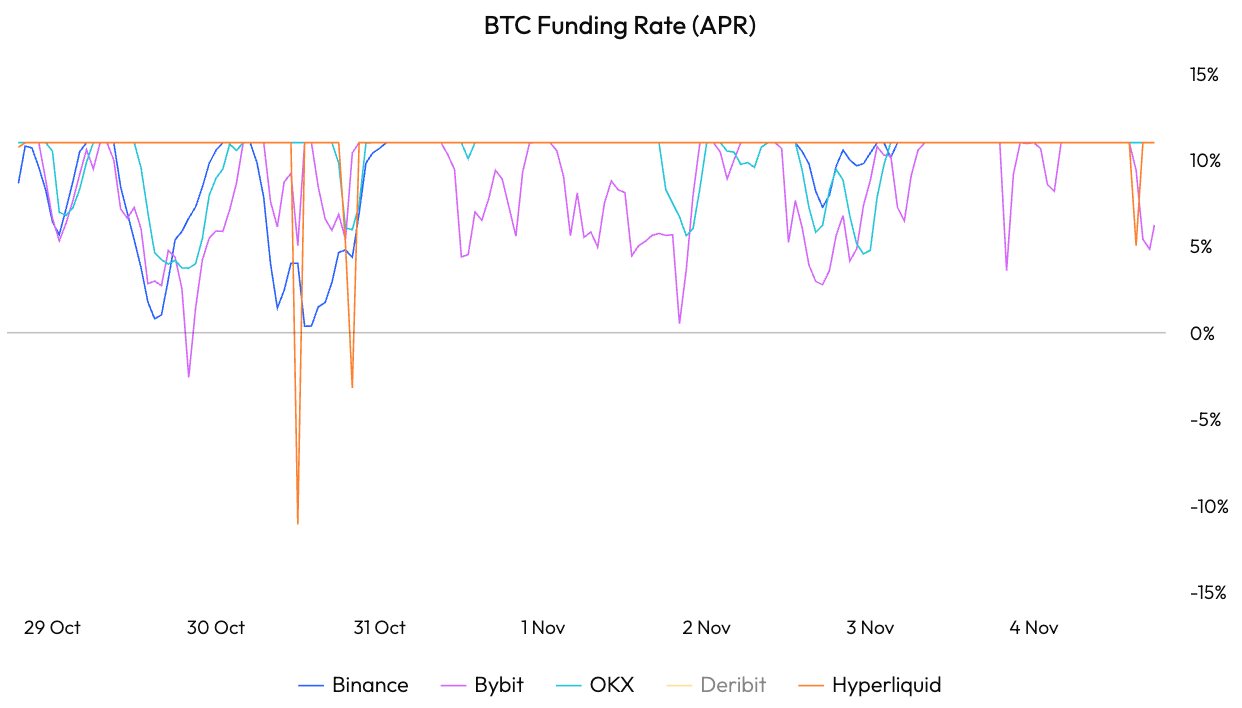
Funding is perhaps the most interesting part of the futures market. Despite BTC trading near recent lows, perpetual funding remains firmly positive. Longs are paying to hold exposure even after the recent sell-off. Funding at these levels is not extreme, but the fact that it has remained positive through a meaningful drawdown suggests leveraged positioning has not capitulated.
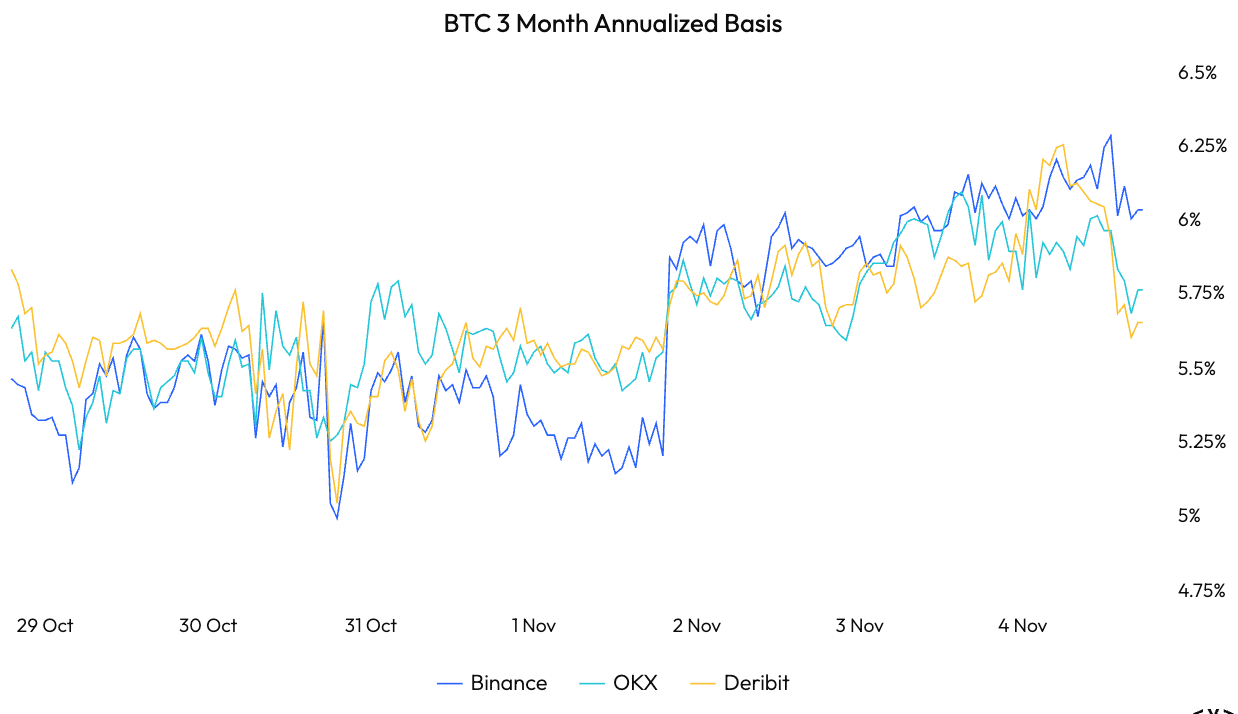
Dated futures tell a similar story. December BTC basis is currently around 5.8–6.3% annualised across the major liquid contracts. March 2027 basis is slightly flatter at approximately 5.0–5.8%. Basis has therefore held — and in parts of the curve actually firmed — despite spot weakness. This is quite different from a stressed derivatives market, where we would normally expect the curve to compress sharply toward spot or move into backwardation.
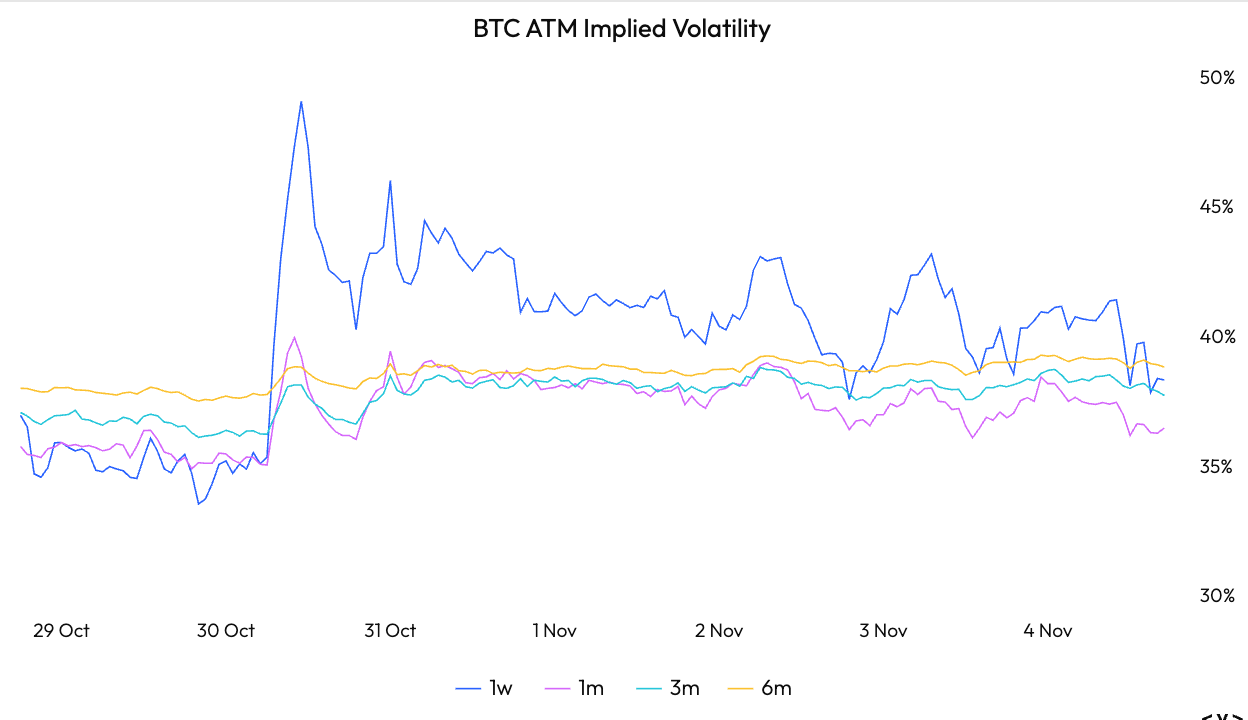
Options markets have absorbed considerably more of the stress. During Thursday’s sell-off, 1-week ATM implied volatility jumped 6.1 volatility points in a single day. The move was concentrated at the front of the curve: six-month IV increased only 0.3 vols over the same period to 38.7%.
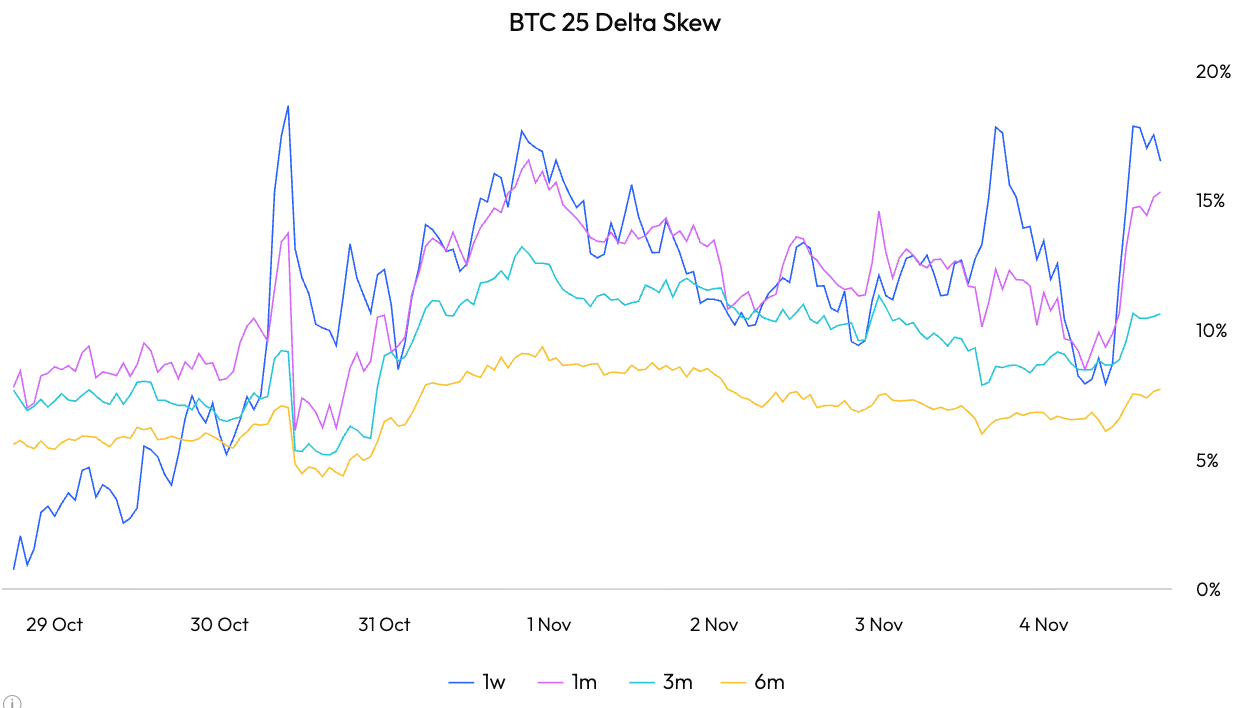
Skew moved even more defensively. At the end of last week, 1-week 25-delta risk reversal reached -5.4 vols and 2-week -5.6 vols, meaning puts were trading at a substantial implied-volatility premium to equivalent calls. That fear premium moderated, but we are seeing a jump as of Wednesday 04 Nov, most likely driven by the US midterm results hitting the wires.
Absolute volatility is also beginning to normalise. 1-week ATM IV is now approximately 39.7%, versus 7-day realised volatility of 36.2%, while 1-month IV is 37.6%, 3-month 38.1% and 9-month 39.5%. The volatility curve is therefore remarkably flat beyond the immediate front end. Investors are paying a premium for near-term uncertainty — particularly around the U.S. midterm outcome and Friday’s payrolls release — but are not pricing a structurally higher volatility regime further out.
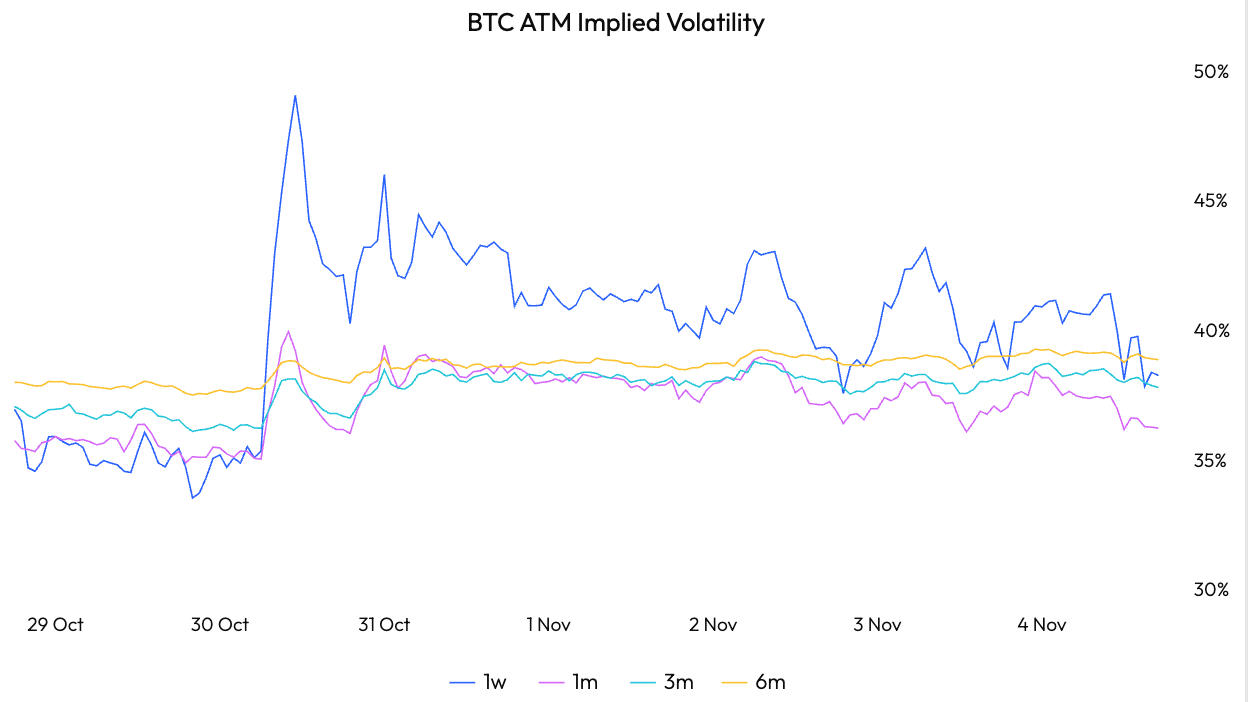
Overall, the derivatives complex is sending a more nuanced signal than spot alone. Downside protection has repriced, but leverage has not collapsed. Funding remains positive, dated basis remains around 6%, and longer-dated volatility is still anchored around the high-30s. That looks more like investors actively hedging a difficult macro and crypto-specific environment than a market experiencing forced capitulation.
Safe trading out there!
Jon de Wet, CIO
What to Watch
Tue: RBA Interest Rate Decision
Wed: US Midterm Elections, EA Inflation Rate YoY
Thu: BoE Interest Rate Decision, AU Balance of Trade
Fri: US Non Farm Payrolls, US Unemployment Rate
Contact Us
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
DISCLAIMER
Zerocap Pty Ltd carries out regulated and unregulated activities.
Spot crypto-asset services and products offered by Zerocap are not regulated by ASIC. Zerocap Pty Ltd is registered with AUSTRAC as a DCE (digital currency exchange) service provider (DCE100635539-001).
Regulated services and products include structured products (derivatives) and funds (managed investment schemes) are available to Wholesale Clients only as per Sections 761GA and 708(10) of the Corporations Act 2001 (Cth) (Sophisticated/Wholesale Client). To serve these products, Zerocap Pty Ltd is a Corporate Authorised Representative (CAR: 001289130) of AFSL 340799
This material is intended solely for the information of the particular person to whom it was provided by Zerocap and should not be relied upon by any other person. The information contained in this material is general in nature and does not constitute advice, take into account financial objectives or situation of an investor; nor a recommendation to deal. . Any recipients of this material acknowledge and agree that they must conduct and have conducted their own due diligence investigation and have not relied upon any representations of Zerocap, its officers, employees, representatives or associates. Zerocap has not independently verified the information contained in this material. Zerocap assumes no responsibility for updating any information, views or opinions contained in this material or for correcting any error or omission which may become apparent after the material has been issued. Zerocap does not give any warranty as to the accuracy, reliability or completeness of advice or information which is contained in this material. Except insofar as liability under any statute cannot be excluded, Zerocap and its officers, employees, representatives or associates do not accept any liability (whether arising in contract, in tort or negligence or otherwise) for any error or omission in this material or for any resulting loss or damage (whether direct, indirect, consequential or otherwise) suffered by the recipient of this material or any other person. This is a private communication and was not intended for public circulation or publication or for the use of any third party. This material must not be distributed or released in the United States. It may only be provided to persons who are outside the United States and are not acting for the account or benefit of, “US Persons” in connection with transactions that would be “offshore transactions” (as such terms are defined in Regulation S under the U.S. Securities Act of 1933, as amended (the “Securities Act”)). This material does not, and is not intended to, constitute an offer or invitation in the United States, or in any other place or jurisdiction in which, or to any person to whom, it would not be lawful to make such an offer or invitation. If you are not the intended recipient of this material, please notify Zerocap immediately and destroy all copies of this material, whether held in electronic or printed form or otherwise.
Disclosure of Interest: Zerocap, its officers, employees, representatives and associates within the meaning of Chapter 7 of the Corporations Act may receive commissions and management fees from transactions involving securities referred to in this material (which its representatives may directly share) and may from time to time hold interests in the assets referred to in this material. Investors should consider this material as only a single factor in making their investment decision.
Past performance is not indicative of future performance.
Like this article? Share
 Share
 Tweet
 Post

Latest Insights
Weekly Crypto Market Wrap: 26 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 20 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 12 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Receive Our Insights
Subscribe to receive our publications in newsletter format — the best way to stay informed about crypto asset market trends and topics.