


21 Sep, 26
Weekly Crypto Market Wrap: 21 September 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
This is not financial advice. As always, do your own research.
Week in Review
- U.S. spot Bitcoin ETFs finished the week with US$6.2M in net inflows on strong two-way volumes; Ethereum ETFs shed US$140M to snap a four-week inflow streak.
- SEC unveiled five-year innovation exemptions for tokenized stock platforms and liquidity providers; dealer registration requirements are delayed.
- The CLARITY Act failed to advance in the U.S. Senate; CFTC filed crypto asset markets rulemaking with the White House, pressing ahead despite the legislative setback.
- Derive (DRV) and Paradex (DIME) tokens surged as institutional-style onchain options infrastructure expands; Derive posted record weekly notional volume of US$1.5B.
- Crypto.com’s Nadex exchange registered with the SEC for single-stock futures, with plans to offer U.S. single-stock perps.
Technicals & Macro
Markets
The Federal Reserve delivered its first rate increase in more than three years on Wednesday, raising the funds rate 25 basis points to 3.75 to 4.00 percent in a unanimous 12-0 vote. The statement was characteristically brief, noting that inflation remains elevated and that the Committee will deliver price stability. The dot plot carried the message: 16 of 18 participants project at least one further increase this year and four see two, with no hikes pencilled in beyond 2026. Chair Warsh again declined to submit a projection, reiterated that he is not in the forward guidance business, and signalled a preference for the balance sheet over the policy rate as the primary inflation tool. Markets now price roughly a 55 percent chance of a further move on 28 October and around 90 percent by December.
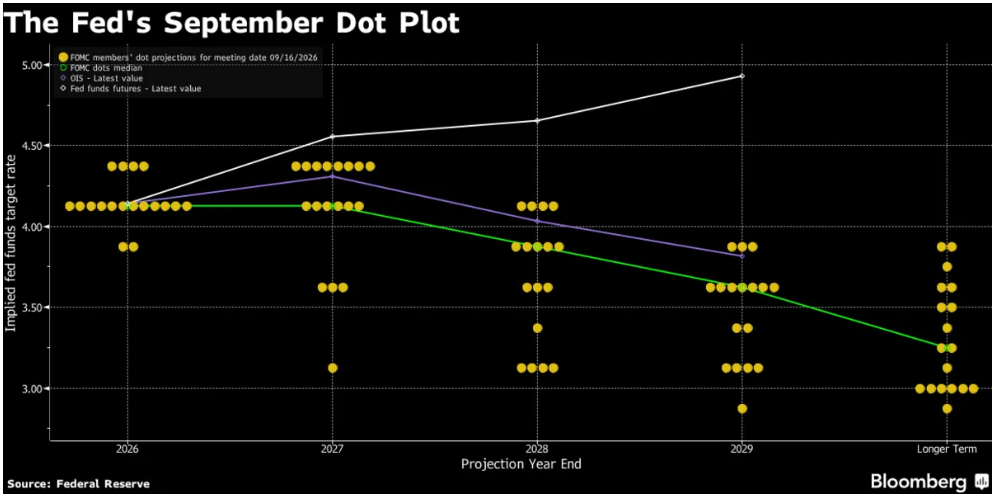
Source: Federal Reserve
The long end did not wait for confirmation. The 10-year yield topped 5 percent early in the week for the first time since July 2007, eased on Thursday, and closed Friday back at 5.006 percent as Middle East supply uncertainty lifted fuel and natural gas prices. The Bank of Japan followed on Friday with a 25 basis point increase to 1.25 percent, its highest since 1995, though two dissents and no commitment to further tightening left the yen weaker rather than stronger.
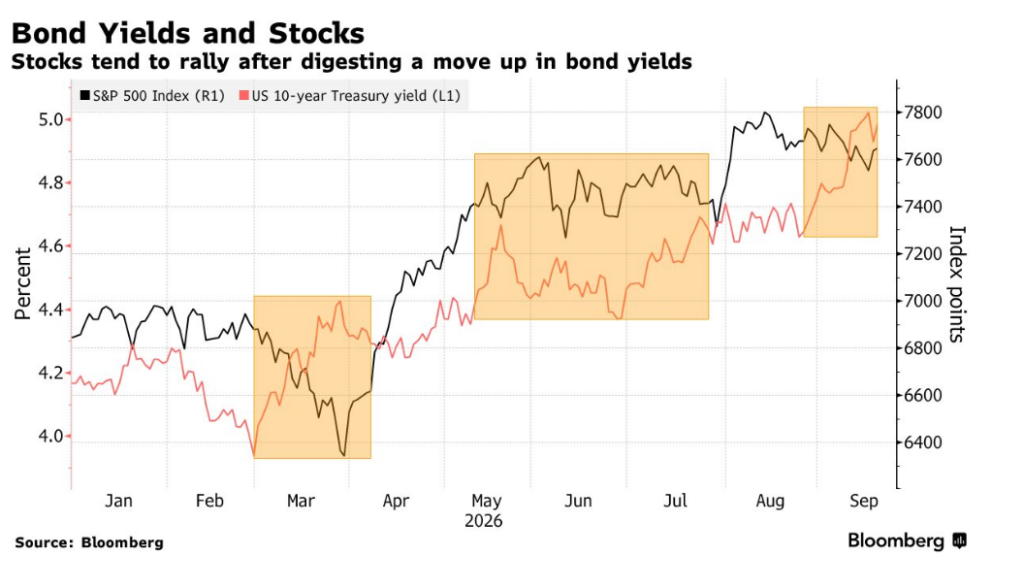
In equity markets, the week’s path is more informative than its outcome. Semiconductors and AI infrastructure names sold off on Monday as markets digested the weekend call from the leading frontier labs to pace AI development, equities retreated on Wednesday after the hike, and both the S&P 500 and Nasdaq reclaimed their 50-day moving averages on Thursday before Friday’s triple-witching session faded alongside the rebound in yields. Friday’s Dow was weighed by IBM, Disney and Nike, partly offset by Amgen, Nvidia and Caterpillar. Year to date the S&P 500 is up 11.8 percent and the Nasdaq 14.1 percent.
Cryptocurrency
Digital assets delivered the week’s most striking performance, absorbing three consecutive negative catalysts and finishing materially higher. Bitcoin trades at US$81,407 this morning, up approximately 5.5 percent on the week and within reach of the 4 September high of US$82,284. Ether outperformed at US$2,656, up roughly 11 percent, and Solana sits at US$111.23.
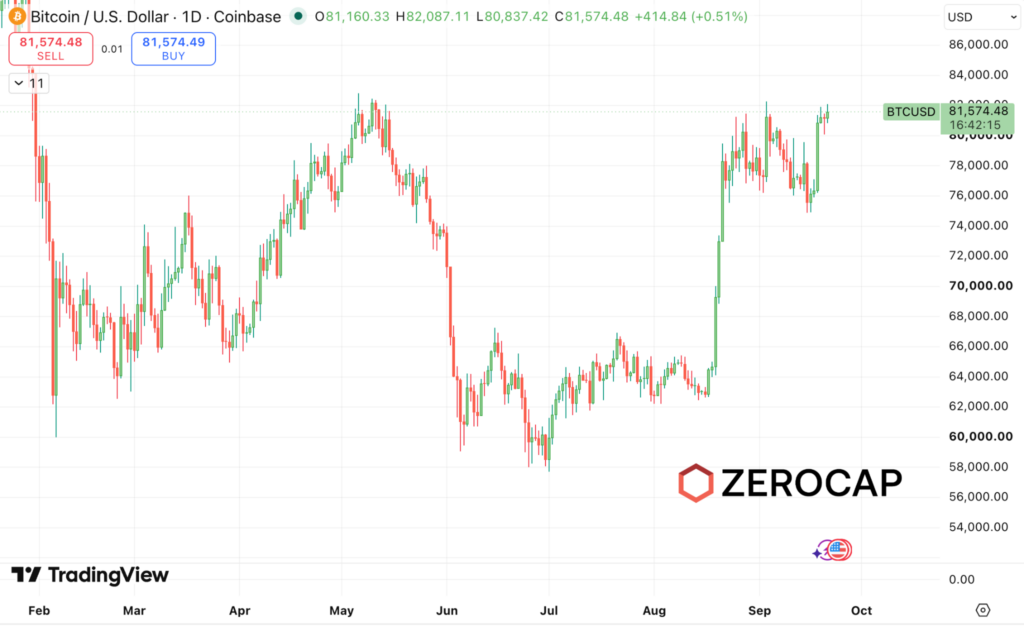
On Tuesday the Senate failed to invoke cloture on the CLARITY Act, 49 to 50, falling not only short of 60 but short of a simple majority, with no Democrats in support and four Republicans opposed. The bill is effectively dead for 2026. On Wednesday the Fed hiked and signalled more to come. Through the week the 10-year held at 5 percent. Bitcoin dipped below US$76,000 around the vote and recovered every dollar. Bitwise’s Matt Hougan made the relevant point: Bitcoin rose from approximately US$57,950 on 1 July to above US$80,000 by early September while Polymarket odds of passage fell from 39 percent to 14 percent, which suggests the rally was never dependent on the legislation. With the SEC’s Regulation Crypto Assets framework open for comment until 20 October and Chair Atkins stating the agency will deliver with or without Congress, US rulemaking now passes to the regulators.
The breadth of the move was the defining feature. On Friday, 98 of the 100 CoinDesk 100 constituents advanced, led by a rotation into layer-2 and DeFi tokens. Arbitrum gained 25 percent over 24 hours to its highest since January and trades near US$0.217 this morning. Starknet rose 21 percent to its highest since June, Uniswap gained up to 25 percent with futures open interest near a record, and the DeFi Select Index added 8.3 percent. Optimism and Stacks each gained around 9 percent. Within Solana, the Raydium DEX token rose 16 percent while liquid-staking token Jito added only 1.6 percent, a split that points to DEX volume rather than a blanket bid for the chain. Thursday’s leadership had come from privacy and perceived haven assets, with Zcash advancing 7.6 percent over 24 hours to around US$1,490, so the Friday rotation into DeFi and scaling tokens represents a clear shift toward risk-on positioning.
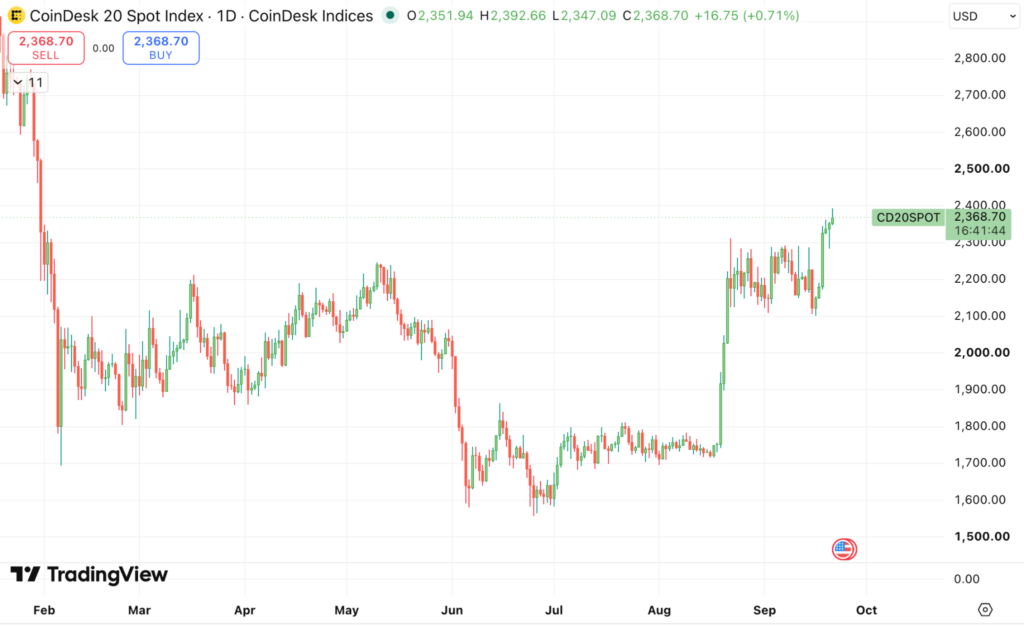
The positioning data supports the move without flagging excess. CoinMarketCap’s Altcoin Season Index rose to 44 from 32 on Tuesday, the Fear and Greed Index reads 73, and total crypto market capitalization stands at US$2.77 trillion. Aggregate futures open interest expanded nearly 5 percent to US$141.2 billion while daily volume contracted 3 percent to US$95 billion, a divergence that indicates capital is entering through structured positioning rather than momentum chasing.
Fund flows were more mixed and worth reading carefully. Spot Bitcoin ETFs recorded just US$6.2 million of net inflows, the smallest in 141 weeks of trading, but gross movement was US$1.5 billion: outflows of US$450 million and US$296 million around the CLARITY vote and the FOMC were almost entirely recovered by US$159 million on Thursday and US$433 million on Friday, led by a US$310.7 million Fidelity FBTC day. Spot Ether ETFs posted a US$140 million weekly outflow, ending a four-week streak that had gathered US$1.94 billion. Solana ETFs extended their inflow run to 12 consecutive weeks. We would note two cautions: DeFi total value locked is down 39 percent year to date at approximately US$70 billion, so the rally in DeFi tokens is running ahead of the underlying activity, and a US$3.5 million oracle exploit on Starknet lending protocol Nostra on Friday is a reminder that ecosystem risk accompanies ecosystem beta.
Technically, US$82,000 is the level where sellers have repeatedly stopped the advance, with a break above US$81,300 opening a low-volume zone toward US$86,500. We regard the combination of a failed regulatory catalyst, a hawkish Fed and a 5 percent 10-year producing a 5.5 percent Bitcoin gain and near-universal altcoin participation as the strongest evidence yet that the market has decoupled from the policy calendar that dominated the first half.
Emir Ibrahim
Spot Desk
Digital assets traded a clear two-sided week, with an early risk-off bleed around the CLARITY Act’s failed US Senate vote and the FOMC hike fully retraced into the weekend as majors led a strong recovery through Friday’s US session. Bitcoin (BTC) rallied from US$76,842 to US$81,178, returning to the upper end of the range that has contained price action since August’s expansion, while Ethereum (ETH) advanced from US$2,477 to US$2,645 – outperforming as ETH/BTC firmed. Institutional flows mirrored the round trip: with heavy midweek redemptions reversed by significant late-week creations, leaving BTC ETFs remarkably balanced at US$6M of net inflows against over US$1.5B of gross turnover – highlighting engaged but increasingly two-way institutional participation rather than the typically directional nature of the channel.
Desk activity broadly reflected the mixed tape; BTC reverted to a modest net selling skew, while ETH was bid as the SEC’s innovation exemption provided a constructive regulatory offset to the CLARITY setback. Desk flows ran counter to broader market activity, where spot ETH ETFs notched US$140M in net outflows to snap a four-week inflow streak. Amidst the longer tail, Hyperliquid (HYPE) and Bittensor (TAO) attracted buying interest, while DOT and TON were offered in the aggregate. In price action, Zcash (ZEC) extended into fresh highs as it remained a standout performer, while Derive (DRV) and Paradex (DIME) made parabolic moves to push sharply into price discovery as on-chain options and derivatives infrastructure became a key narrative capturing crypto-native mindshare.
Stablecoins remained a major component of desk volume. USDT was significantly net sold as clients continued to favour operational USD liquidity, while USDC diverged with a net on-ramping skew – a recurring feature in recent weeks as USDC becomes increasingly embedded as collateral across on-chain derivatives venues as the link between stablecoin demand and renewed risk deployment strengthens. AUD-denominated fiat alternative rails also remained active, with AUDM net bought and AUDD net sold across predominantly treasury-related flows.
In FX, AUD/USD softened from 0.7159 to 0.7122, trading as low as 0.7074 around Wednesday’s FOMC before recovering into the weekly close. The Fed’s unanimous 25bp hike to 3.75–4.00% reinforced the US tightening bias, while renewed Middle East escalation added a further USD safe-haven bid and pushed crude above US$107/bbl. Domestically, RBA tightening expectations strengthened materially after Governor Bullock warned that upside inflation risks were beginning to materialise; markets are now pricing roughly an 86% probability of a cash rate hike to 4.60% at the September 29 meeting, while experts have brought their base-case hike forward from November to September. With both central banks now leaning hawkish, the bilateral yield differential is providing less directional signal than earlier in the year, leaving AUD increasingly driven by external US Dollar strength and broader geopolitical risks despite firm domestic policy support.
The OTC desk continues to provide tailored cryptocurrency liquidity solutions and competitive pricing across major digital assets, stablecoins, selected altcoins and key fiat currency pairs. With T+0 settlement capability, the desk continues to facilitate efficient execution and settlement across client flows.
Ben Mensah, OTC Trader
Derivatives Desk
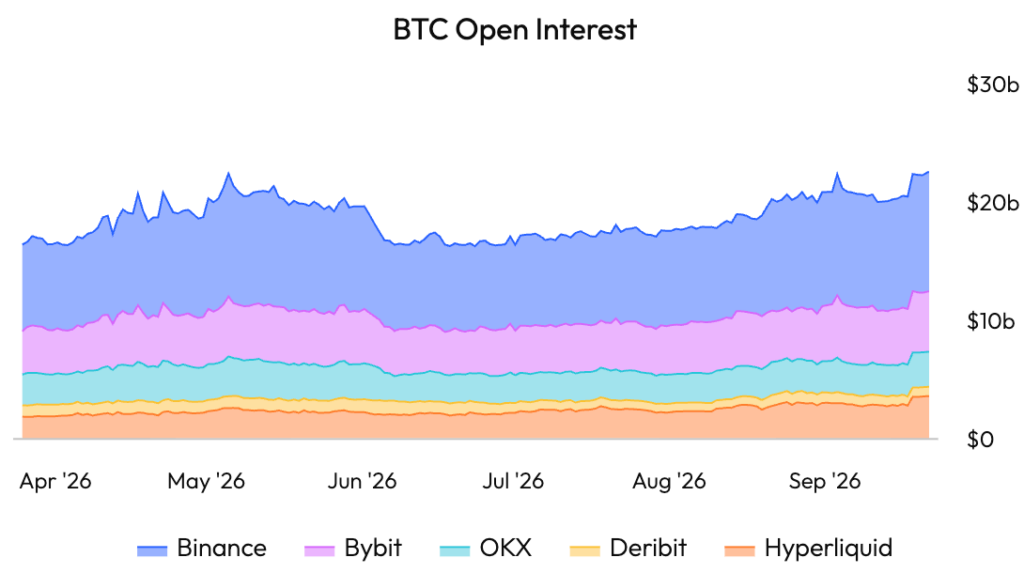
Bitcoin rallied sharply into the end of last week with derivatives activity picking up alongside spot. The move followed the Federal Reserve’s 25bp hike on 16 September, its first since 2023, which took the target range to 3.75–4.00%. BTC dipped briefly on the decision before recovering above $80k within two days. BTC futures open interest across Binance, Bybit, OKX, Deribit and Hyperliquid stands at approximately $22–23bn, back to its late-April high. However, the increase since August has broadly tracked the rise in price, implying limited growth in BTC-denominated leverage. Despite the increase in activity, leverage still doesn’t yet look excessive.
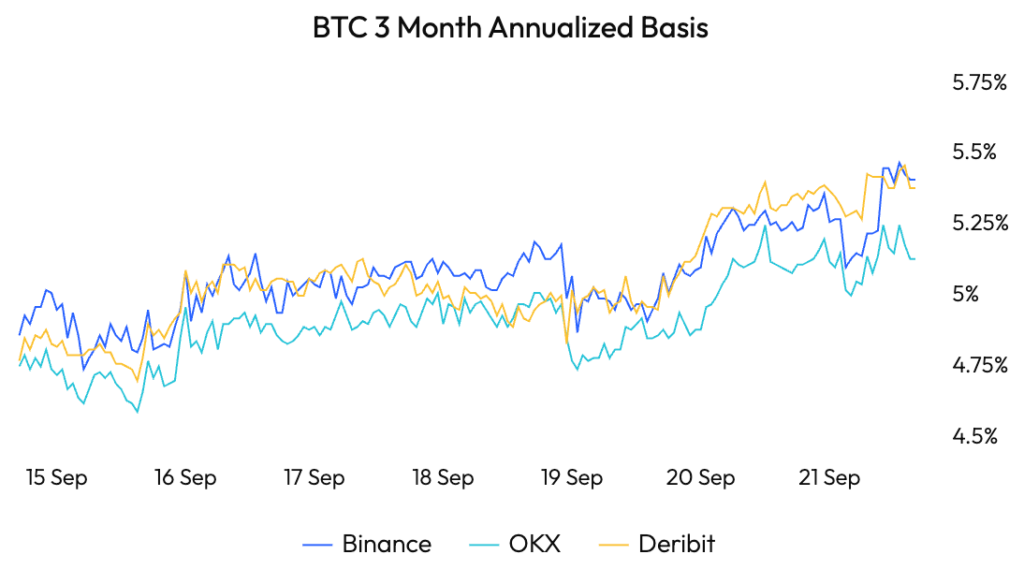
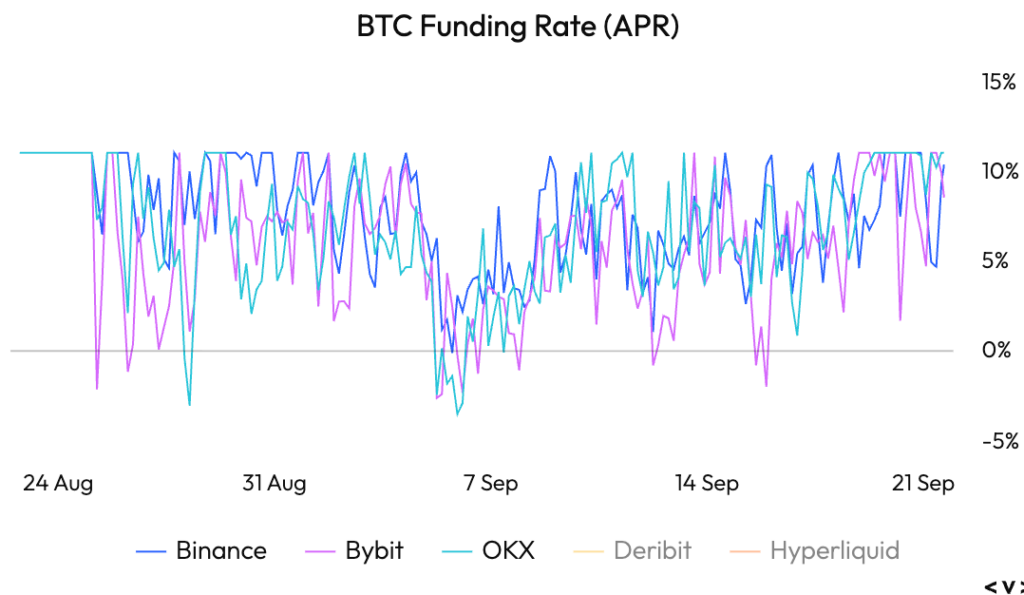
The longer-dated futures curve remains relatively restrained. BTC annualised basis is sitting broadly around 5–6% across October–December maturities, with December contracts around 5.2–5.5% on Binance and Bybit. Funding is positive across most major perpetual venues, but still relatively contained — around 7–11% annualised across Binance, Bybit and OKX at the latest observations. This suggests leveraged longs have returned, but we are still some way from the stressed funding and basis levels typically associated with late-stage speculative positioning.
Source: Velo.xyz
The 3-month basis is particularly interesting – the desk view is that it will normalise at some point in the near future. With interest rates rising, it is nonsensical to have a basis curve below what you’d earn from bank paper.
The options market provides a similarly interesting picture. During the week, BTC 2-week 25-delta risk reversal moved from -0.66 to +1.16 vols, showing a clear shift in demand toward upside calls as BTC broke higher. At the same time, implied volatility declined across much of the curve: 1-week ATM IV finished Friday at 34.6%, 1-month at 34.3% and 3-month at 36.8%, down from roughly 38–39% ahead of the FOMC. Part of that decline reflects event premium rolling off after the Fed decision and the Senate’s Clarity Act procedural vote, rather than purely a calm market.
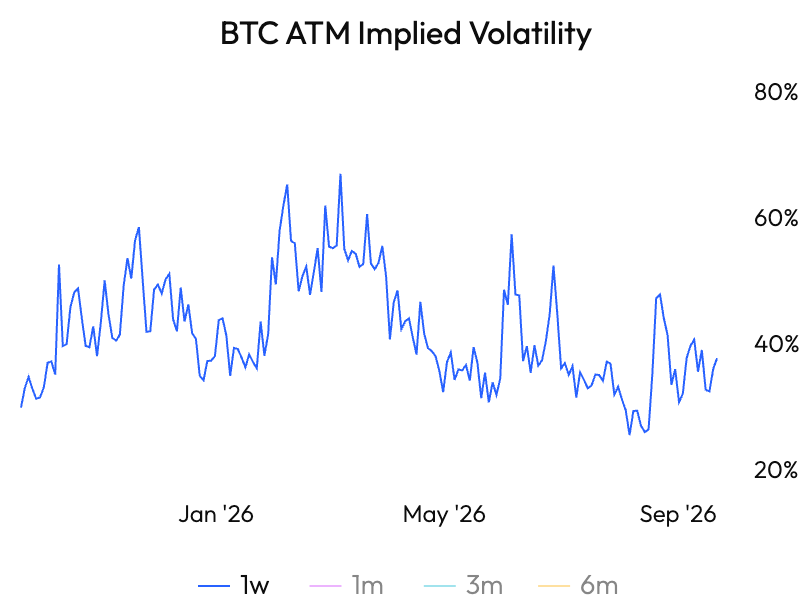
Importantly, that upside enthusiasm has already moderated. By Sunday the 2-week risk reversal had moved back to -0.26 vols, while 2-week ATM IV eased to 33.7%. One-week implied volatility of 34.0% also remained below seven-day realised volatility of 37.1%. The takeaway is that BTC has rallied without a corresponding explosion in implied volatility or persistent call skew — a relatively healthy setup versus previous highly leveraged rallies.
Trade Idea: Harvesting carry while leverage remains contained
Despite believing that the futures basis will expand, the BTC futures curve continues to offer ~5–6% annualised gross cash-and-carry returns across medium-dated expiries. With the Fed now at 3.75–4.00% and reserve balances paying 3.90%, that is a spread of roughly 1.5 percentage points over USD cash, before execution costs. I would put this trade in the entry bucket – size it small, with the expectation that when the basis expands further, you will be able to roll to a higher interest rate upon expiration.
- Existing BTC holders: Selling December futures against spot already held locks in ~5% annualised in USD terms with no cash opportunity cost. That is attractive while outright directional volatility remains elevated, although you lose BTC upside if it rallies.
- USD holders: the incremental return over cash is modest. Investors should weigh it against the counterparty exposure to the exchanges holding the futures leg.
- Further hikes: the Fed’s updated projections point to at least one more hike this year, which would narrow the spread further.
Key risks:
- Venue counterparty risk on the futures leg.
- Margin calls on the short future if BTC rallies sharply, so hold sufficient collateral headroom.
- Basis compression, which leaves mark-to-market P&L volatile before expiry.
For directional BTC holders, we would also look for opportunities to sell upside volatility on renewed spikes in call skew, rather than mechanically selling calls at current levels. With 1-week implied volatility trading below realised, option sellers are currently not being well compensated. Friday demonstrated how quickly upside demand can reprice when BTC moves through key levels, while Sunday’s reversal in skew shows that these windows can be short-lived.
Overall, the derivatives market is sending a fairly constructive signal: price has moved higher through a Fed hike, leverage has rebuilt, but neither basis nor options pricing are flashing signs of excess just yet. The main constraint on carry strategies is now the higher USD rate backdrop rather than market positioning.
Safe trading out there!
Jon de Wet
CIO
Safe trading out there!
Jon de Wet
CIO
What to Watch
Tue: RBA Hunter Speech
Wed: Fed Williams Speech, US MBA 30-Year Mortgage Rate, KR Consumer Confidence
Thu: AU Unemployment Rate, President Trump & President XI Summit, US Initial Jobless Claims
Fri: Fed Paulson Speech, US New Home Sales, MX Interest Rate Decision
Contact Us
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
DISCLAIMER
Zerocap Pty Ltd carries out regulated and unregulated activities.
Spot crypto-asset services and products offered by Zerocap are not regulated by ASIC. Zerocap Pty Ltd is registered with AUSTRAC as a DCE (digital currency exchange) service provider (DCE100635539-001).
Regulated services and products include structured products (derivatives) and funds (managed investment schemes) are available to Wholesale Clients only as per Sections 761GA and 708(10) of the Corporations Act 2001 (Cth) (Sophisticated/Wholesale Client). To serve these products, Zerocap Pty Ltd is a Corporate Authorised Representative (CAR: 001289130) of AFSL 340799
This material is intended solely for the information of the particular person to whom it was provided by Zerocap and should not be relied upon by any other person. The information contained in this material is general in nature and does not constitute advice, take into account financial objectives or situation of an investor; nor a recommendation to deal. . Any recipients of this material acknowledge and agree that they must conduct and have conducted their own due diligence investigation and have not relied upon any representations of Zerocap, its officers, employees, representatives or associates. Zerocap has not independently verified the information contained in this material. Zerocap assumes no responsibility for updating any information, views or opinions contained in this material or for correcting any error or omission which may become apparent after the material has been issued. Zerocap does not give any warranty as to the accuracy, reliability or completeness of advice or information which is contained in this material. Except insofar as liability under any statute cannot be excluded, Zerocap and its officers, employees, representatives or associates do not accept any liability (whether arising in contract, in tort or negligence or otherwise) for any error or omission in this material or for any resulting loss or damage (whether direct, indirect, consequential or otherwise) suffered by the recipient of this material or any other person. This is a private communication and was not intended for public circulation or publication or for the use of any third party. This material must not be distributed or released in the United States. It may only be provided to persons who are outside the United States and are not acting for the account or benefit of, “US Persons” in connection with transactions that would be “offshore transactions” (as such terms are defined in Regulation S under the U.S. Securities Act of 1933, as amended (the “Securities Act”)). This material does not, and is not intended to, constitute an offer or invitation in the United States, or in any other place or jurisdiction in which, or to any person to whom, it would not be lawful to make such an offer or invitation. If you are not the intended recipient of this material, please notify Zerocap immediately and destroy all copies of this material, whether held in electronic or printed form or otherwise.
Disclosure of Interest: Zerocap, its officers, employees, representatives and associates within the meaning of Chapter 7 of the Corporations Act may receive commissions and management fees from transactions involving securities referred to in this material (which its representatives may directly share) and may from time to time hold interests in the assets referred to in this material. Investors should consider this material as only a single factor in making their investment decision.
Past performance is not indicative of future performance.
Like this article? Share
 Share
 Tweet
 Post

Latest Insights
Weekly Crypto Market Wrap: 14 September 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 8 September 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 31 August 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Receive Our Insights
Subscribe to receive our publications in newsletter format — the best way to stay informed about crypto asset market trends and topics.