


13 Oct, 26
Weekly Crypto Market Wrap: 12 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
This is not financial advice. As always, do your own research.
Week in Review
- Robinhood added US$25M of bitcoin to its balance sheet, reinforcing its broader push into digital assets.
- Ethereum researcher Justin Drake warned on private key recovery risks amid continued AI progress; Vitalik Buterin urged careful planning rather than rushed wallet migrations.
- U.S. spot Bitcoin ETF products shed US$681.1M; Ethereum ETFs lost US$542.1M while Solana ETFs saw net redemptions to snap a 14-week inflow streak.
- Securitize launched 1:1-backed tokenized stocks, starting with Apple, Nvidia and Strategy as onchain stock value surpassed US$3B.
- Ledger-linked security concerns resurfaced after authorised reseller CryptoBilis buyers reported wallet drains, with estimated losses now above US$86M.
Technicals & Macro
Markets
The bond market reasserted itself last week. The 10-year Treasury yield touched 5.36 percent on Wednesday, its highest level since 2002, and the 30-year reached a 24-year high near 5.67 percent, as elevated oil prices, heavy government issuance and AI-related corporate borrowing kept pressure on the long end. A strong US$39 billion 10-year auction pulled yields back to around 5.28 percent by Wednesday’s close, but the direction of travel remains unchanged. The FOMC minutes, released the same afternoon, showed all officials supported September’s hike and that most see a further increase as appropriate before year-end, though they gave no indication of timing. That reinforces our read from last week: the market has priced out October, with odds near 20 percent, but not the tightening cycle, and December remains the favoured meeting for the next move.
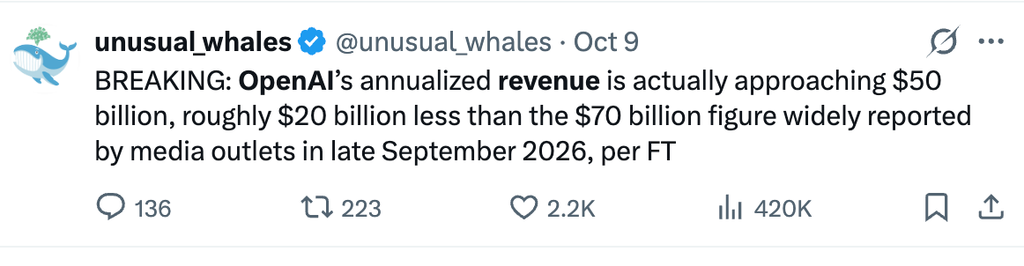
Equities looked past the rates pressure. The S&P 500 set a record of 7,844.52 on Tuesday and closed the week up 1.2 percent at 7,811.54, the Dow gained 0.9 percent to 51,654.95, and the Nasdaq rose 0.6 percent to 27,366.17 for a fourth consecutive weekly gain. That came despite a Thursday sell-off in technology after reports that OpenAI’s annualised revenue had reached US$50 billion, below what the market had been pricing for the AI trade. The more striking single-sector move was in telecommunications: SpaceX agreed to acquire a nationwide 800MHz spectrum portfolio to take Starlink into mobile, sending T-Mobile down 13.3 percent, AT&T 9.8 percent and Verizon 8.75 percent, its worst session since 2002.
Source: x.com
Brent traded back toward US$106 on Thursday on continued Hormuz uncertainty before easing into the weekend, while gold softened to US$4,221 alongside a firmer dollar. This week’s US CPI and PPI releases, together with the start of the Q3 bank earnings season, are now the decisive inputs ahead of the 27-28 October FOMC.
Cryptocurrency
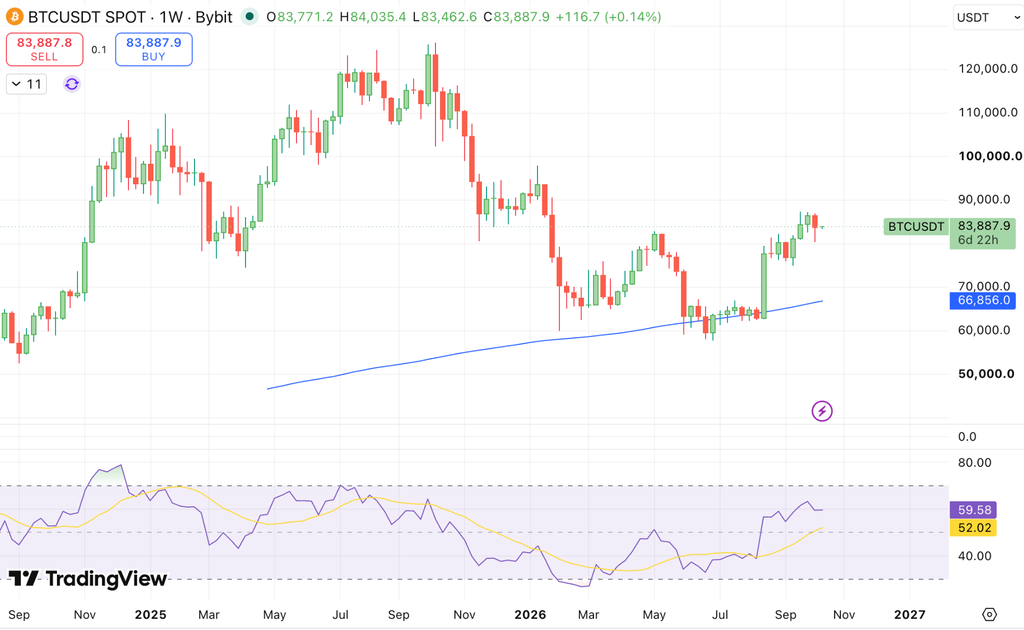
Crypto parted ways with equities and took the brunt of the rates move. Bitcoin opened the week near US$87,000, failed again at the US$87,000 to US$88,000 resistance zone, and fell to around US$80,400 on Thursday as the hawkish minutes, rising yields and oil above US$100 combined with a crowded long position. More than US$1.1 billion of leveraged positions were liquidated over 24 hours, of which roughly 95 percent were longs, with Ether liquidations exceeding Bitcoin’s. CryptoQuant data showed around 25,700 BTC of profit-taking in the week prior, the largest of 2026. Bitcoin trades near US$83,838 this morning, down approximately 2 percent on the week.
We would characterise the move as a leverage flush rather than a change in trend. The leverage that rebuilt through the late-September rally has now been cleared, Bitcoin held the US$80,000 level, and the scale of Thursday’s liquidations was a small fraction of last October’s US$19 billion event. Bitcoin’s relative resilience was notable: dominance rose to around 59 percent as Ether fell roughly 5.5 percent to US$2,552 and Solana around 7 percent to US$111.96, both declining close to three times as far as Bitcoin.
Against that backdrop, altcoin strength was confined to a handful of names. Starknet was the standout, rising around 88 percent to US$0.12, its highest since late 2025, while Bitway extended its run by around 35 percent toward US$1.70 and Aerodrome gained 11 percent. Sky was among the weakest, down 17 percent. With the broader complex lower and dominance rising, this looks like selective, catalyst-driven buying rather than a sustained rotation out of Bitcoin.
The US$80,000 level, which approximates the average cost basis of ETF holders, is now the line that matters. Having held through a heavy liquidation event, it provides a defined base; a break below would put recent ETF buyers underwater and risk redemption-driven selling. This week’s US inflation data is the near-term catalyst, and with the 10-year above 5.25 percent, the opportunity cost of holding non-yielding assets remains the binding constraint on the next leg higher.
For any pricing needs, please get in touch.
Emir Ibrahim
Spot Desk
Digital assets traded defensively through the week as broader rates pressure and renewed risk aversion across the AI complex filtered into liquidity-sensitive assets. The reported shortfall in OpenAI’s annualised revenue resurfaced scrutiny around AI valuations, while Ethereum security researchers separately flagged AI-accelerated mathematical progress as a potential challenge to existing cryptographic security assumptions. Bitcoin (BTC) softened from US$86,530 to around US$83,838, while Ethereum (ETH) underperformed as ETH/BTC moved lower; with the passive channel weakening materially as BTC, ETH and SOL products all recorded significant outflows. Majors recovered modestly through the weekend, however, and have held well within recent ranges into Monday’s Asia session, showing early signs of strength against the pressured narrative and macro backdrop.
Client activity broadly reflected the softer institutional tone; BTC carried a net selling skew in line with passive redemptions, while ETH was modestly net bought – a countertrend signal against both weaker relative performance and persistent ETF outflows. Breadth across the wider complex remained limited, although Bittensor (TAO) and Venice (VVV) attracted interest as decentralised AI narratives continued to capture crypto-native mindshare. Overall, positioning remained highly selective rather than indicative of a broader rotation back into altcoin beta.
In stablecoins, USDT was significantly off-ramped into USD as secondary-market pricing softened below parity alongside the weaker spot tape. USDC diverged materially, recording its strongest on-ramping week of the year and extending a recurring split between the two major dollar stablecoins – potentially reflecting its growing role as collateral and settlement liquidity across in-favour on-chain derivatives venues including Derive, Paradex and Hyperliquid. AUDD was also significantly net sold for on-ramping purposes, continuing a pattern that has persisted across market regimes.
In FX, AUD/USD reversed four consecutive weekly declines, opening at 0.6955 and closing modestly firmer at 0.6982 despite meaningful intraweek volatility. AUD remained caught between elevated global yields and a still-hawkish domestic policy backdrop, while movements in DXY continued to provide the dominant higher-frequency impulse. Domestically, October consumer sentiment fell 4.7% to 80.4, with the September RBA hike driving a sharp deterioration among respondents surveyed after the decision. This week’s US CPI print and Fed Chair Warsh speaking on Friday provide the key external tests for the Fed rates path and USD direction, while Thursday’s Australian labour-force print will offer the clearest local read on whether tighter policy is beginning to transmit more visibly into activity; together, the releases should set the near-term relative-rates impulse for AUD/USD. On the desk, AUD was significantly off-ramped, EUR remained offered, NZD was bought, and GBP flows were broadly balanced.
The OTC desk continues to provide tailored cryptocurrency liquidity solutions and competitive pricing across major digital assets, stablecoins, selected altcoins and key fiat currency pairs. With T+0 settlement capability, the desk continues to facilitate efficient execution and settlement across client flows.
Ben Mensah, OTC Trader
Derivatives Desk
WHOLESALE INVESTORS ONLY
BTC has given back part of the prior week’s rally, trading down ~3.2% over seven days. Futures positioning has also cooled. CoinGlass currently shows aggregate BTC futures open interest down ~7% WoW. Some of that decline is naturally mark-to-market as BTC fell, but taken together with the funding data, the broader picture is one of leverage reduction, rather than aggressively rebuilt.
Perpetual funding has essentially returned to neutral. At the latest snapshot, Binance BTC funding was around -0.0004% per eight hours, OKX -0.0008%, and Bybit +0.0053%; the five-venue average was only +0.0048%. This is a meaningful cooling from the more consistently positive funding prints seen through parts of last week, indicating that longs are not paying a premium for leverage.
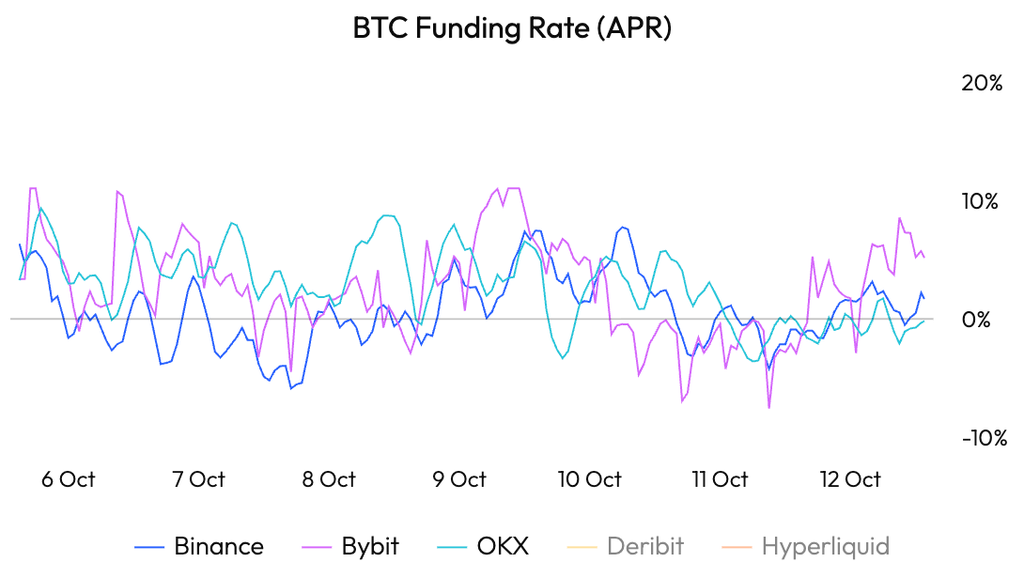
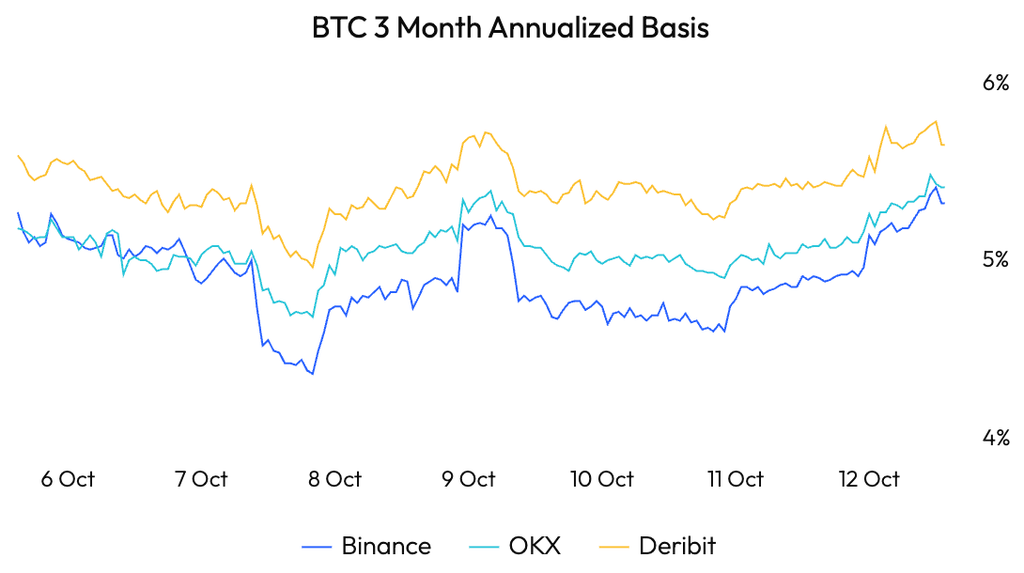
The dated curve is somewhat firmer. December BTC basis is approximately 5.4–5.8% annualised across the major contracts. March 2027 contracts remain around the high-5% area. The distinction between subdued perpetual funding and a healthy dated basis is worth noting: investors are still willing to pay a term premium for BTC exposure, but this is not translating into obvious crowding in the perpetual market.
Options are giving the clearer change in signal this week. Short-dated skew has moved decisively toward puts. At Friday’s snapshot, 1-week 25-delta risk reversal was -2.99 vols, 2-week -3.23 vols and 1-month -2.66 vols, versus the broadly neutral surface we discussed previously. Over the full week, 2-week skew moved 2.94 volatility points toward puts. By Sunday, the average risk reversal across the available headline tenors had moved further to approximately -2.65 vols. Negative risk reversal here means 25-delta puts are trading at a higher implied volatility than equivalent calls.
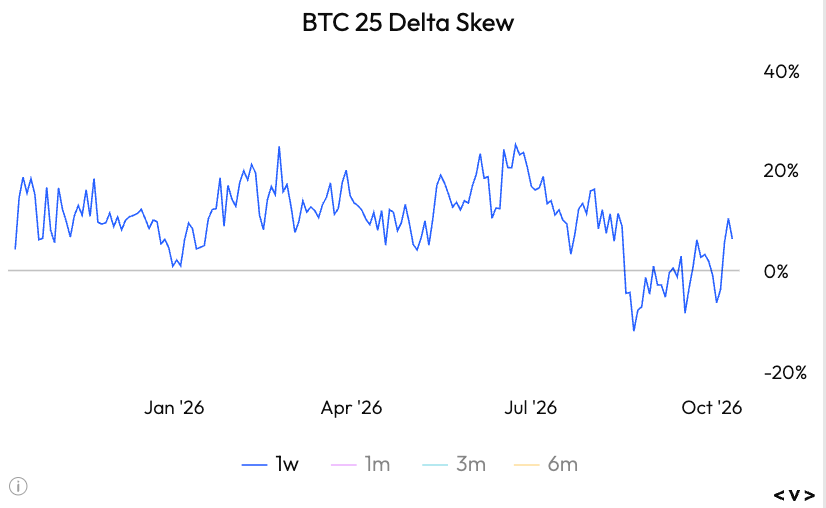
Importantly, that should not be interpreted as the entire options market suddenly turning bearish. Aggregate BTC options open interest is approximately $37.3bn, with calls still representing around 60.5% of outstanding OI. The stock of positioning therefore remains call-heavy; what has changed is the marginal price of protection. Traders are now paying a greater volatility premium for downside puts. This defensive repricing coincides with weaker spot ETF flows — U.S. Bitcoin ETFs recorded approximately $386.3m of net outflows through the first seven trading days of October — although we would not assume a direct causal relationship. en.coinotag.com
Absolute volatility has also repriced modestly higher. As of Sunday, BTC 1-week ATM IV was 32.48%, 1-month 35.51%, 3-month 37.31% and 6-month 38.11%. One-week implied now sits around 2.7 volatility points above seven-day realised volatility of 29.79%. That is a notable change from periods last week where short-dated implied was trading below realised. The upward-sloping term structure remains relatively orderly, however — there is no sign of acute front-end panic despite the richer put skew. derivasys.com
Overall, the derivatives complex has become more defensive, but not stressed. BTC is lower, futures open interest has declined, perpetual funding is close to flat and the dated curve still offers close to 6% annualised carry. The meaningful change is in options: downside protection is becoming more expensive while outright volatility remains relatively contained.
Safe trading out there!
Jon de Wet, CIO
What to Watch
Tue: RBA Meeting Minutes,, Fed Waller Speech
Wed: US Inflation Rate, CN Inflation Rate, ECB President Lagarde Speech
Thu: AU Unemployment Rate, GB GDP, US Core PPI
Fri: US Fed Chair Warsh Speech
Contact Us
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at [email protected]
DISCLAIMER
Zerocap Pty Ltd carries out regulated and unregulated activities.
Spot crypto-asset services and products offered by Zerocap are not regulated by ASIC. Zerocap Pty Ltd is registered with AUSTRAC as a DCE (digital currency exchange) service provider (DCE100635539-001).
Regulated services and products include structured products (derivatives) and funds (managed investment schemes) are available to Wholesale Clients only as per Sections 761GA and 708(10) of the Corporations Act 2001 (Cth) (Sophisticated/Wholesale Client). To serve these products, Zerocap Pty Ltd is a Corporate Authorised Representative (CAR: 001289130) of AFSL 340799
This material is intended solely for the information of the particular person to whom it was provided by Zerocap and should not be relied upon by any other person. The information contained in this material is general in nature and does not constitute advice, take into account financial objectives or situation of an investor; nor a recommendation to deal. . Any recipients of this material acknowledge and agree that they must conduct and have conducted their own due diligence investigation and have not relied upon any representations of Zerocap, its officers, employees, representatives or associates. Zerocap has not independently verified the information contained in this material. Zerocap assumes no responsibility for updating any information, views or opinions contained in this material or for correcting any error or omission which may become apparent after the material has been issued. Zerocap does not give any warranty as to the accuracy, reliability or completeness of advice or information which is contained in this material. Except insofar as liability under any statute cannot be excluded, Zerocap and its officers, employees, representatives or associates do not accept any liability (whether arising in contract, in tort or negligence or otherwise) for any error or omission in this material or for any resulting loss or damage (whether direct, indirect, consequential or otherwise) suffered by the recipient of this material or any other person. This is a private communication and was not intended for public circulation or publication or for the use of any third party. This material must not be distributed or released in the United States. It may only be provided to persons who are outside the United States and are not acting for the account or benefit of, “US Persons” in connection with transactions that would be “offshore transactions” (as such terms are defined in Regulation S under the U.S. Securities Act of 1933, as amended (the “Securities Act”)). This material does not, and is not intended to, constitute an offer or invitation in the United States, or in any other place or jurisdiction in which, or to any person to whom, it would not be lawful to make such an offer or invitation. If you are not the intended recipient of this material, please notify Zerocap immediately and destroy all copies of this material, whether held in electronic or printed form or otherwise.
Disclosure of Interest: Zerocap, its officers, employees, representatives and associates within the meaning of Chapter 7 of the Corporations Act may receive commissions and management fees from transactions involving securities referred to in this material (which its representatives may directly share) and may from time to time hold interests in the assets referred to in this material. Investors should consider this material as only a single factor in making their investment decision.
Past performance is not indicative of future performance.
Like this article? Share
 Share
 Tweet
 Post

Latest Insights
Weekly Crypto Market Wrap: 5 October 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 28 September 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Weekly Crypto Market Wrap: 21 September 2026
Zerocap is a market-leading digital asset firm, providing trading, liquidity and custody to forward-thinking institutions and investors globally. To learn more, contact the team at
Receive Our Insights
Subscribe to receive our publications in newsletter format — the best way to stay informed about crypto asset market trends and topics.